
Best Credit Cards for a Europe Trip in 2026: Low Forex Picks
9 October 2026 · BestCard Editorial Team
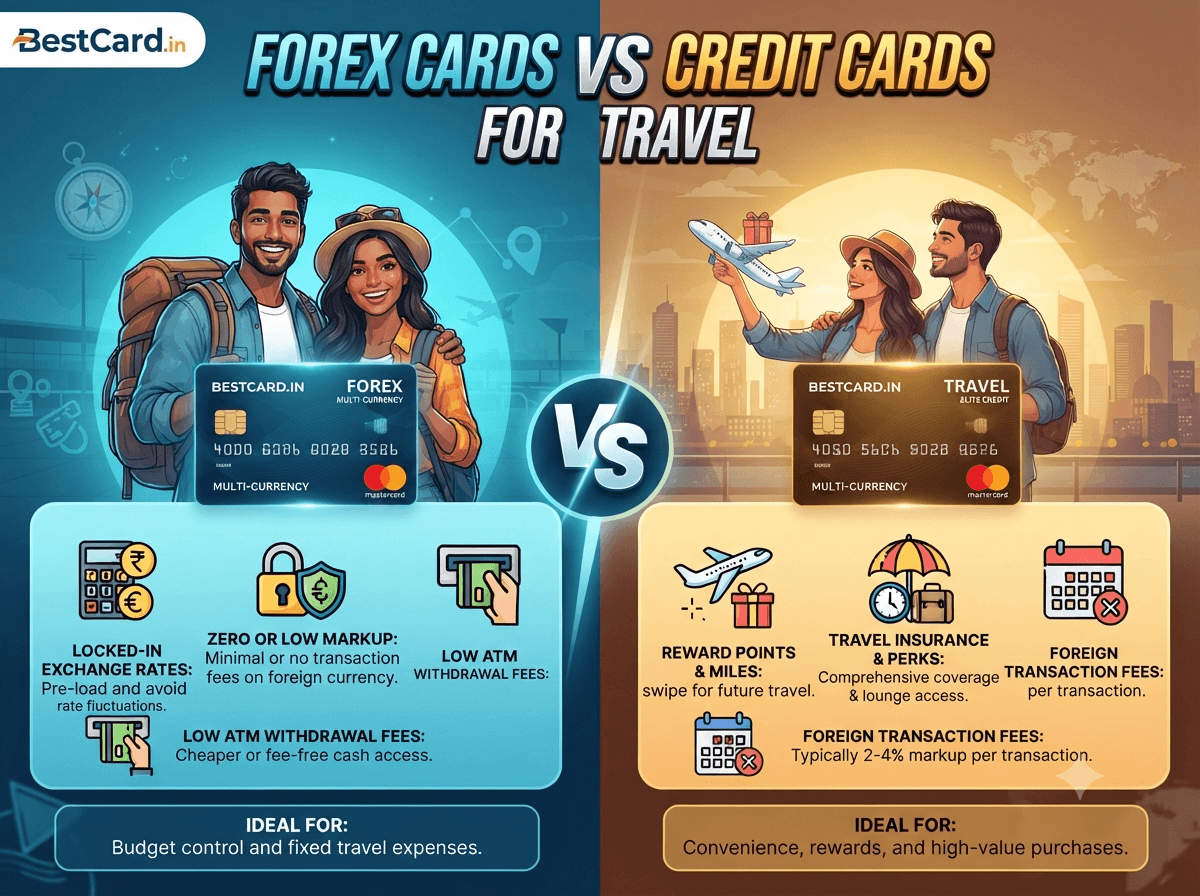
The best credit card for a Europe trip is a Visa or Mastercard with zero or very low forex markup, ideally with some lounge access and travel insurance attached. For most travellers that means a 0% markup card like the Federal Bank Scapia or IDFC FIRST Ashva as the main card, with a second card on a different network as backup.
Europe is card-friendly. Contactless payments are the norm, many cafes and transport machines prefer cards to cash, and hotels and car rental desks expect a card for the deposit. That makes the card you carry matter more than the forex notes in your wallet.
Why forex markup is the number that matters
Every time you pay in euros (or Swiss francs, or Czech koruna), your card issuer converts it to rupees and adds a forex markup. Most Indian cards charge 3.5%, and GST at 18% applies on top of that fee.
Here's what that looks like on a typical two-week trip with ₹2,00,000 of card spends:
| Card markup | Markup fee | GST on fee (18%) | Total extra cost |
|---|---|---|---|
| 3.5% | ₹7,000 | ₹1,260 | ₹8,260 |
| 1.99% | ₹3,980 | ₹716 | ₹4,696 |
| 0% | ₹0 | ₹0 | ₹0 |
That ₹8,260 gap is often larger than the reward points a regular card earns on the same spend. So the first filter is simple: get the markup as low as you can, then look at lounges and insurance.
The shortlist
All figures below come from BestCard's latest card data. Issuers change terms often, so confirm on the issuer's site before applying.
Federal Bank Scapia: best free card for Europe
The Federal Bank Scapia card has no joining or annual fee and a 0% forex markup, which is rare at this price. You earn Scapia Coins worth about 2% on eligible spends and about 4% on flights and hotels booked in the Scapia app, though coins can only be used inside that app. Domestic lounge access is unlimited once you spend ₹5,000 in a month, but there's no international lounge benefit. Minimum income is ₹25,000 a month, so it's within reach for most salaried travellers.
IDFC FIRST Ashva: zero forex plus real lounge access
The IDFC FIRST Ashva costs ₹2,999 a year with no spend waiver, and pairs a 0% markup with 4 domestic and 2 international airport lounge visits per quarter. For a Europe trip, the useful extras are trip cancellation cover up to ₹25,000 (twice a year) and BOGO movie offers back home. Income requirement is ₹1,00,000 a month. One caution: IDFC has said international spends stop earning reward points on several of its cards from 26 October 2026, so treat any IDFC card as a forex-saver first and a rewards card second.
IDFC FIRST Mayura: for frequent international flyers
The IDFC FIRST Mayura steps up to ₹5,999 a year for up to 16 domestic and 16 international lounge visits annually, unlocked by ₹20,000 of monthly spend. It also carries Cancel For Any Reason travel cover reimbursing up to ₹50,000 twice a year on non-refundable flights and hotels, which is valuable when you've prepaid European hotels months in advance. The income bar is about ₹2.08 lakh a month.
RBL World Safari: zero markup with Priority Pass
The RBL World Safari charges ₹3,000 a year, waived on ₹3,00,000 of annual spend. It has a 0% forex markup, a Priority Pass membership with 2 complimentary international lounge visits a year, and complimentary travel insurance cover of USD 100,000. The catch is that international spends don't earn travel points despite the zero markup. Minimum income is ₹40,000 a month, and it's on Mastercard, which is widely accepted across Europe.
SBI Card Miles ELITE: low markup with more lounge visits
The SBI Card Miles ELITE isn't zero-markup, but at 1.99% it's well below the usual 3.5%. You get 8 domestic and 6 international lounge visits a year via Priority Pass, 3% back in Travel Credits on travel spends and 1% on everything else. The fee is ₹4,999, reversed only if you spend ₹15 lakh in a year. With a ₹50,000 monthly income bar, it's the most accessible card here with a solid international lounge allowance.
Niyo Global: a free backup card for cash and ATMs
The Niyo Global card has no fees and a 0% markup, plus markup-free ATM withdrawals abroad on the linked Niyo Global account. Rewards are thin (0.5% base, 1% on travel) and there are no lounges, but as a second card on a separate account it's a cheap safety net if your main card gets blocked.
Summary table
| Card | Annual fee | Forex markup | International lounge | Best for |
|---|---|---|---|---|
| Federal Bank Scapia | ₹0 | 0% | None | Budget travellers |
| IDFC FIRST Ashva | ₹2,999 | 0% | 2 per quarter | Balanced pick |
| IDFC FIRST Mayura | ₹5,999 | 0% | Up to 16 a year | Frequent flyers |
| RBL World Safari | ₹3,000 (waivable) | 0% | 2 a year (Priority Pass) | Insurance and Mastercard acceptance |
| SBI Card Miles ELITE | ₹4,999 | 1.99% | 6 a year | Lounge-heavy trips |
| Niyo Global | ₹0 | 0% | None | Backup card and ATM cash |
Payment habits that save money in Europe
Always pay in local currency. When a terminal or ATM offers to charge you in rupees, decline. That's dynamic currency conversion, and the rate is set by the merchant's provider, not your card network. Our dynamic currency conversion explainer shows how much it costs.
Carry two networks. Visa and Mastercard are accepted almost everywhere in Europe. Amex and Diners Club work at many hotels but are patchy at small merchants, and RuPay acceptance abroad is limited. Keep one Visa and one Mastercard if you can.
Expect deposit holds. Hotels and car rental desks block an amount on your card at check-in. Make sure your credit limit has headroom, and use a credit card rather than a debit card for these holds.
Enable international usage before you fly. Indian cards ship with international transactions switched off by default. Turn on online and contactless international use in your bank app, and set sensible limits.
Know the visa and tax side. Schengen visa fees and service charges are usually paid before the trip, and our guide to paying visa and passport fees by card covers which cards suit them. Rules on TCS for international card spends have changed more than once, so check the current position with your bank or a tax advisor before a big trip.
How to choose
If you travel abroad once a year and want to keep costs at zero, the Federal Bank Scapia plus Niyo Global as backup covers you without any annual fee. If you want lounge access on the way out and travel cover for prepaid bookings, the IDFC FIRST Ashva is the most balanced pick. Frequent flyers who spend ₹20,000 a month anyway should look at the Mayura's lounge count and cancellation cover. If you already hold an SBI relationship and value lounge visits more than the last 2% of forex savings, the Miles ELITE works well.
Not sure which fits your spending? Try the BestCard matcher to see cards ranked for your profile.
Frequently asked questions
Which credit card is best for spending in Europe?
A Visa or Mastercard with zero forex markup saves the most on everyday euro spends. Federal Bank Scapia, IDFC FIRST Ashva and Niyo Global all list a 0% markup in BestCard's data, while SBI Card Miles ELITE charges 1.99% but adds Priority Pass lounge visits.
Should I pay in euros or rupees when a European card machine asks?
Always pay in euros (the local currency). Choosing rupees triggers dynamic currency conversion, where the merchant's provider sets the exchange rate, and that rate is usually worse than your card network's.
Do Amex and Diners Club cards work in Europe?
They work at many hotels and larger merchants, but acceptance is patchier than Visa and Mastercard, especially at small cafes, shops and transport machines. Carry at least one Visa or Mastercard as your main card.
How much does a 3.5% forex markup cost on a Europe trip?
On ₹2,00,000 of euro spending, a 3.5% markup is ₹7,000, plus 18% GST on that fee, so about ₹8,260 in total. A zero-markup card avoids that charge entirely.
Related reading
- Best Credit Cards for a Thailand Trip in 2026 (Low Forex Picks)
Best credit cards for a Thailand trip in 2026: zero and low forex markup cards like Scapia, AU ixigo and RBL World Safari, with lounge access and rupee maths.
- Best Credit Cards for a Singapore Trip from India (2026)
Best credit cards for a Singapore trip: zero and low forex markup picks, KrisFlyer miles cards, lounge access and a worked example of what forex costs.
- Best Credit Cards for Honeymoon Travel in 2026 (India Picks)
Best credit cards for honeymoon travel from India in 2026: zero-forex picks, lounge cards that cover your spouse, hotel and airline transfers, and forex maths.