Business Credit Cards in India: A Practical Guide
5 November 2024 · BestCard Editorial Team
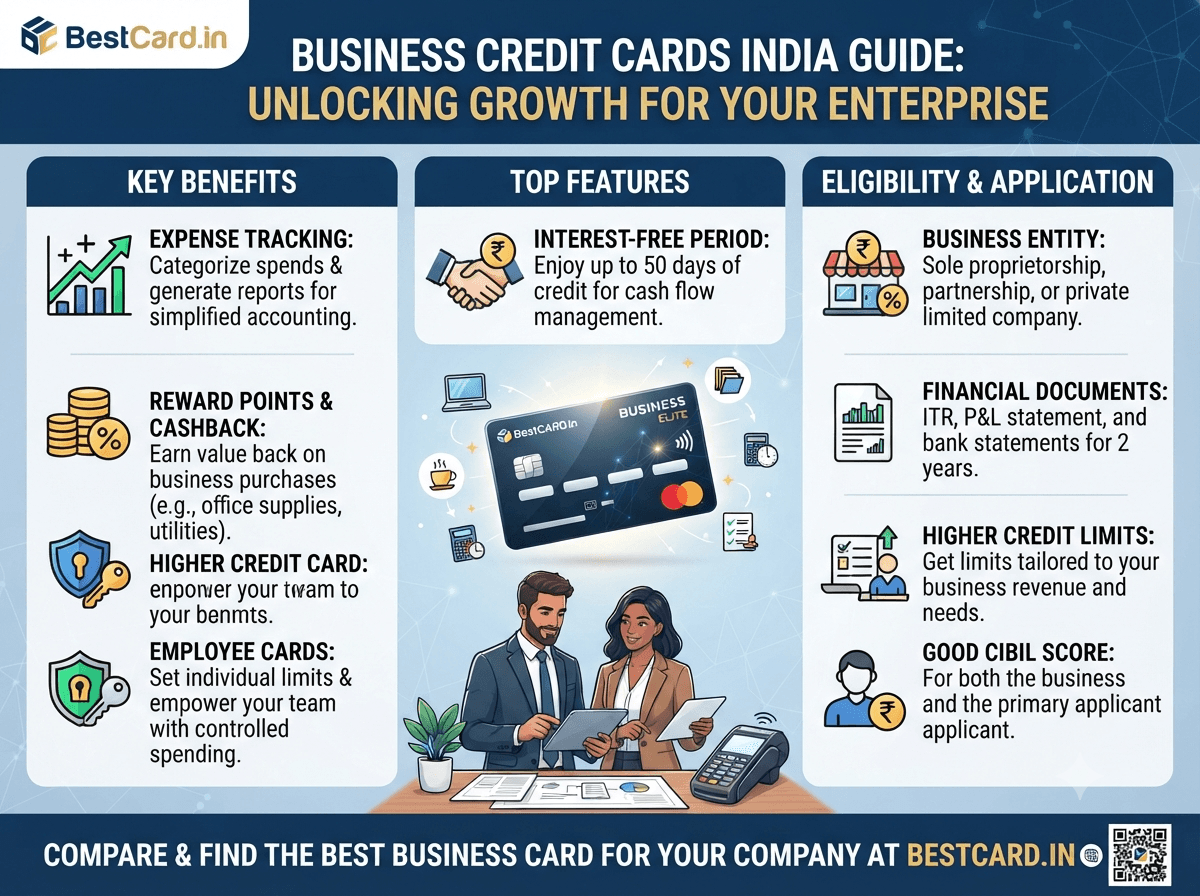
A business credit card in India is not simply a personal card with a company name on it. It's underwritten differently, often tied to your firm's turnover or your own income if you're a sole proprietor, and it usually comes with expense-tracking tools that a personal card skips entirely.
What actually changes with a business card
Most business cards issued by Indian banks give you itemised statements by spend category, multiple add-on cards for employees with individual limits, and sometimes GST-compliant invoices for redemption purchases — useful if your accountant needs to reconcile spending against input tax credit. The reward structure also tends to lean toward categories a business actually spends on: fuel, courier and logistics, office supplies, and digital advertising, rather than travel or dining.
The eligibility bar is where things get inconsistent. Some banks want a registered business (GST or Udyam) and two years of financials; others will issue a card to a sole proprietor purely on personal income and CIBIL score, treating it as a personal card with a business label. If you're a freelancer or a one-person consultancy, ask upfront which category you'll be underwritten as — it changes the documents you need.
Should you get one instead of a personal card
If your business spending is genuinely separate from personal spending — different vendors, recurring subscriptions, employee reimbursements — a business card keeps your accounting cleaner and can unlock reward rates a general card won't match. If you're a small operation where the two blur together anyway, SBI Card or a comparable personal card with strong everyday categories may serve you just as well without the paperwork.
What to check before applying
Look at the annual fee against your actual monthly spend, not the advertised reward rate — many business cards only clear their fee if you're running six-figure monthly volume through them. Also confirm whether the card reports to your personal CIBIL file or stays off it entirely, since that affects your personal credit profile either way.
Where to go from here
If you're self-employed rather than running a registered business, our guide to cards for self-employed professionals is a closer fit, and freelancers specifically should read best credit cards for freelancers in India before deciding between a business and personal card.