
Should You Ask for a Credit Limit Increase or Get a New Card?
15 February 2026 · BestCard Editorial Team
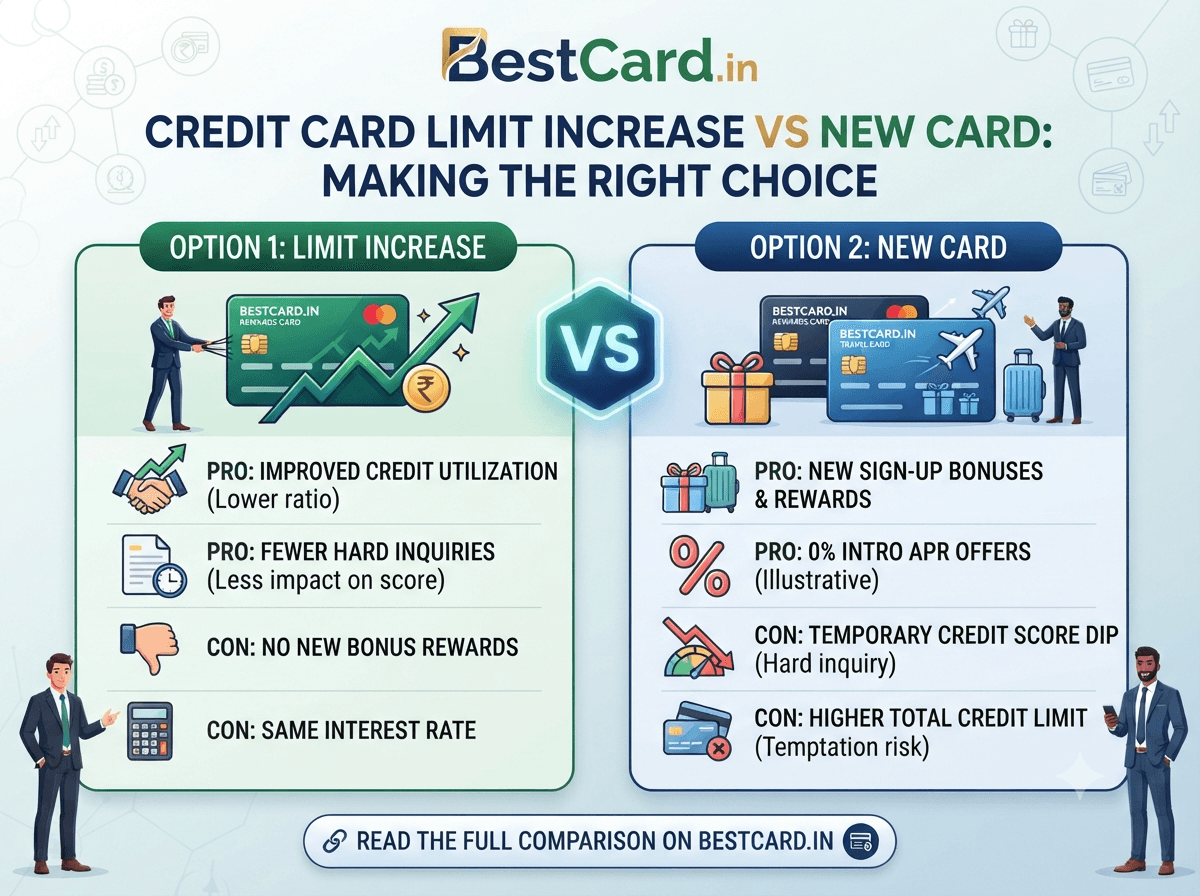
When you're bumping against your credit limit every month, there are two ways out: ask your existing issuer for a higher limit, or apply for a second card. Both solve the immediate cash-flow problem, but they pull on different levers and carry different downstream effects.
The case for a limit increase
A limit increase on a card you already have doesn't touch your credit utilization ratio in a bad way — in fact it improves it instantly, since the same spending now sits against a bigger denominator. It also avoids a fresh hard inquiry in most cases, since many issuers run limit reviews using your existing relationship data rather than a full fresh application. If your income has genuinely grown since you got the card, this is usually the lower-friction option.
The case for a new card
A second card makes more sense when you want access to a different rewards category — a fuel-focused card if your existing one is a shopping card, for instance — rather than just more headroom on the same spending pattern. It also means a second card issuer relationship, which can be useful diversification if your primary bank ever restricts or reviews your account.
What to actually weigh
A new card means a new hard inquiry and a new account that temporarily lowers your average account age — both minor, short-term dents to your CIBIL score. A limit increase, when granted without a hard pull, avoids both. If you're not chasing a specific reward category, the limit increase is usually the lazier and safer path.
Where to go from here
Our guide on how to increase your credit card limit covers the request process itself, and how many credit cards should you have is worth reading before you commit to a second card.
Related reading
- Best Credit Cards Under ₹500 Annual Fee in India (2026)
Best credit cards under ₹500 annual fee for 2026: Axis ACE, Flipkart Axis, Swiggy HDFC, SBI SimplyCLICK, IDFC Power+ and Amex SmartEarn, with caps and waivers.
- Lifetime Free vs Paid Credit Card: Which Should You Choose?
Lifetime free or paid credit card? Use a simple break-even formula, real examples from cards like SBI Cashback and Amazon Pay ICICI, and avoid the common traps.
- Dynamic Currency Conversion Explained: Always Pay Local
Dynamic currency conversion explained: why paying in rupees abroad costs more, a worked example, how to spot DCC at terminals and ATMs, and which cards help.