Forex Cards vs Credit Cards: Which Should You Use While Traveling
19 May 2025 · BestCard Editorial Team
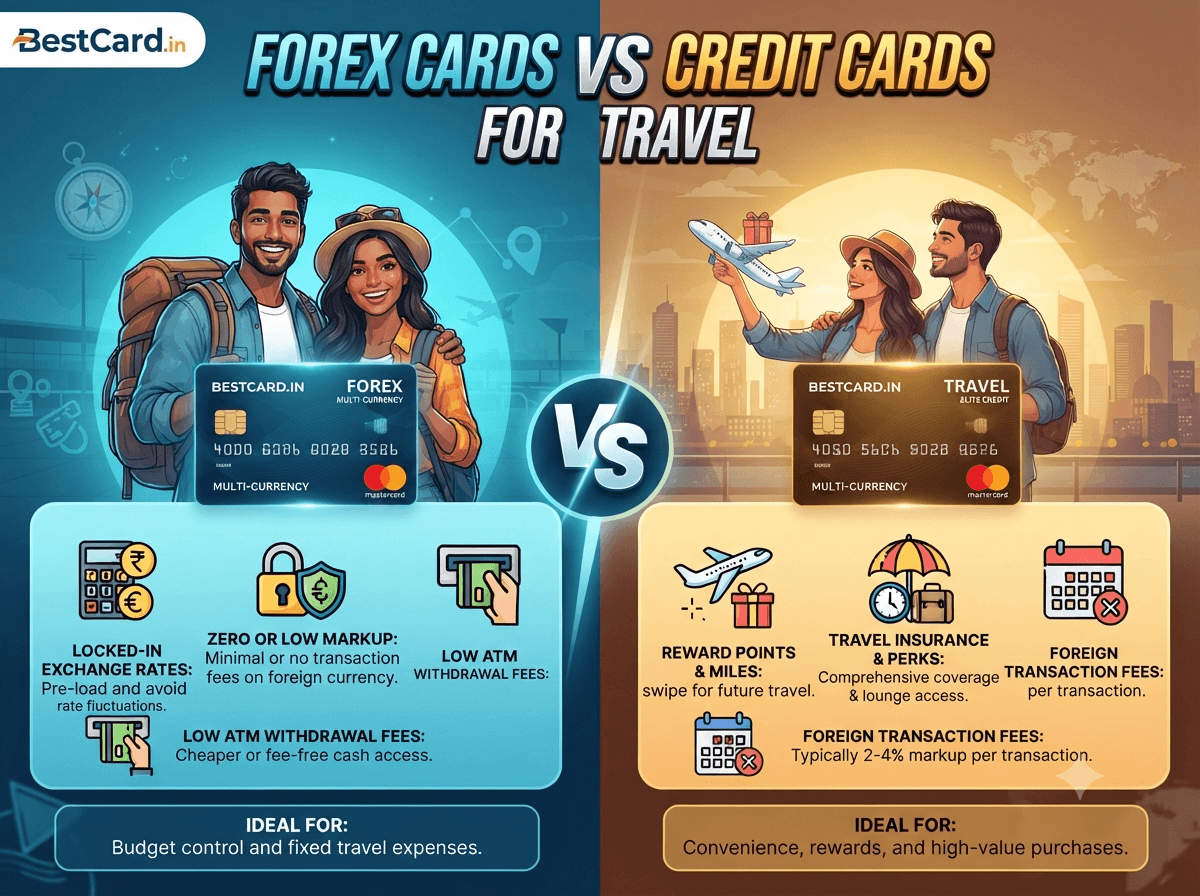
Travelers heading abroad usually default to whichever card is already in their wallet, but forex prepaid cards and credit cards handle foreign spending differently enough that the choice affects your total trip cost.
How the fee structures differ
A forex card locks in an exchange rate at the time you load it, so your rate is fixed regardless of how the rupee moves during your trip — useful if you're loading a large amount before a long trip and expect the rupee to weaken. A credit card charges whatever the markup fee is on each transaction, applied to the live exchange rate at the time of the swipe, which can work for or against you depending on currency movement.
Credit cards with a low forex markup — some are as low as 0-2% versus the standard 3.5% — can actually beat a forex card's loading spread on a like-for-like basis, especially for smaller, spread-out purchases rather than one large upfront load.
Protection and flexibility
A credit card gives you chargeback rights and fraud protection that a prepaid forex card typically doesn't match, and it doesn't require locking up cash in advance the way loading a forex card does. The downside is currency conversion dynamic pricing at some foreign merchant terminals, which credit card holders should always decline in favor of being billed in local currency.
The practical recommendation
For most travelers, a low forex-markup credit card covers day-to-day spending better than a forex card, while a small forex card balance is still worth carrying as a backup for merchants that don't accept cards or in case your primary card gets blocked abroad.
Where to go from here
Check our guide to low forex markup credit cards in India for specific picks, and read how foreign transaction markup fees actually work before your next trip.