The Hidden Traps in 'No Cost EMI' Credit Card Offers
3 February 2025 · BestCard Editorial Team
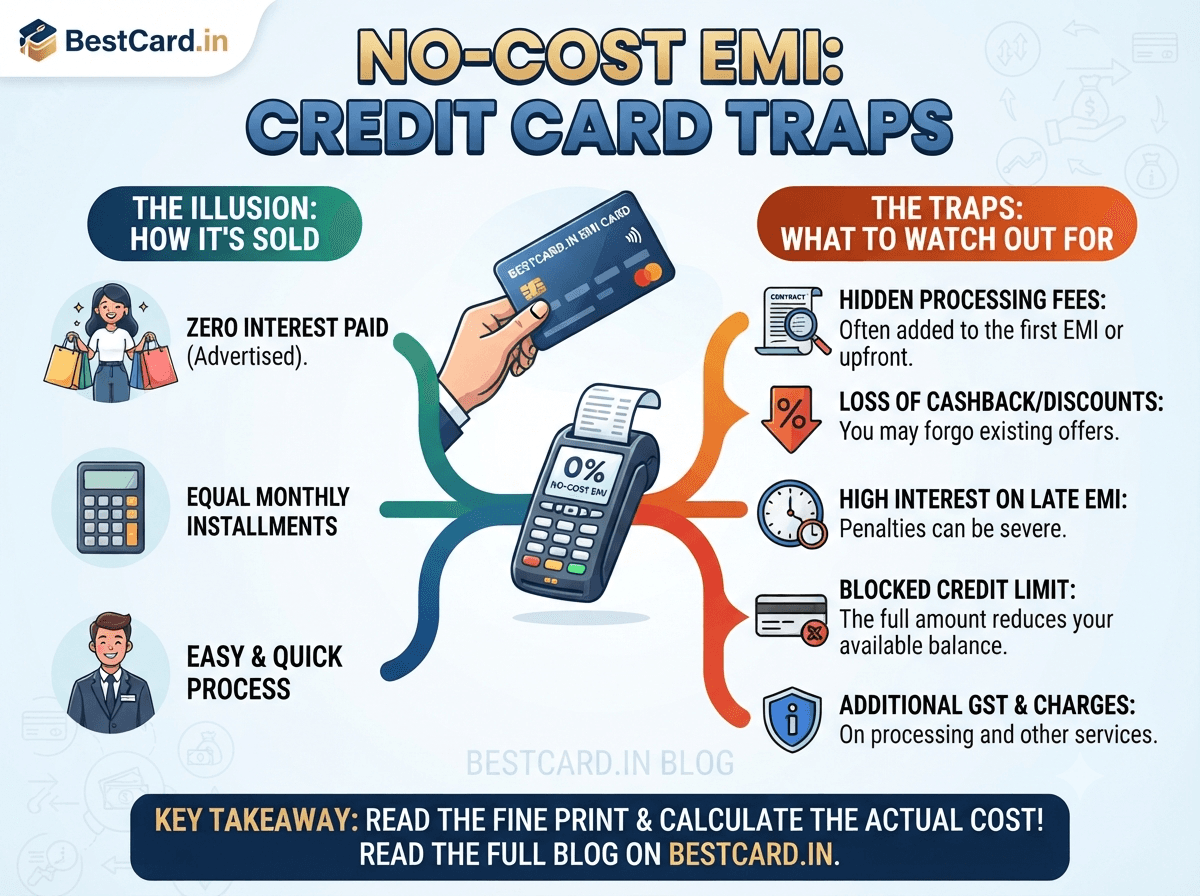
"No cost EMI" is one of the most misleading phrases in Indian retail finance — it implies you're paying zero extra for the convenience of splitting a purchase into monthly installments, and that's rarely the full picture.
Where the cost actually hides
In most no-cost EMI schemes, the merchant gives up the product discount you'd have gotten by paying the full amount upfront, and that forfeited discount is exactly how the "interest" gets baked in — you're not charged interest by name, but you're also not getting the price you would have paid in cash. On top of that, most banks charge a processing fee on EMI conversion, typically 1-2% of the transaction, which is genuinely an extra cost regardless of what the scheme is called.
GST on the interest component
A less obvious trap: even on no-cost EMI, GST is charged on the interest portion embedded in the deal, so you'll often see a small GST line item on your statement that wouldn't exist if you'd paid in full. It's a small amount individually, but across several EMI purchases in a year it adds up.
When EMI conversion still makes sense
Converting a large purchase to EMI is reasonable when you genuinely need the cash flow spread out and the processing fee is smaller than the interest you'd otherwise pay on a personal loan for the same amount. It's a bad idea when you're using it just because the checkout page offered it, on a purchase you could have paid for outright.
Where to go from here
Read our full credit card EMI conversion guide for the mechanics, and our list of credit card mistakes that cost you money covers several other checkout-time traps like this one.