Yes Bank vs HDFC Credit Cards: Which Should You Choose
2 July 2025 · BestCard Editorial Team
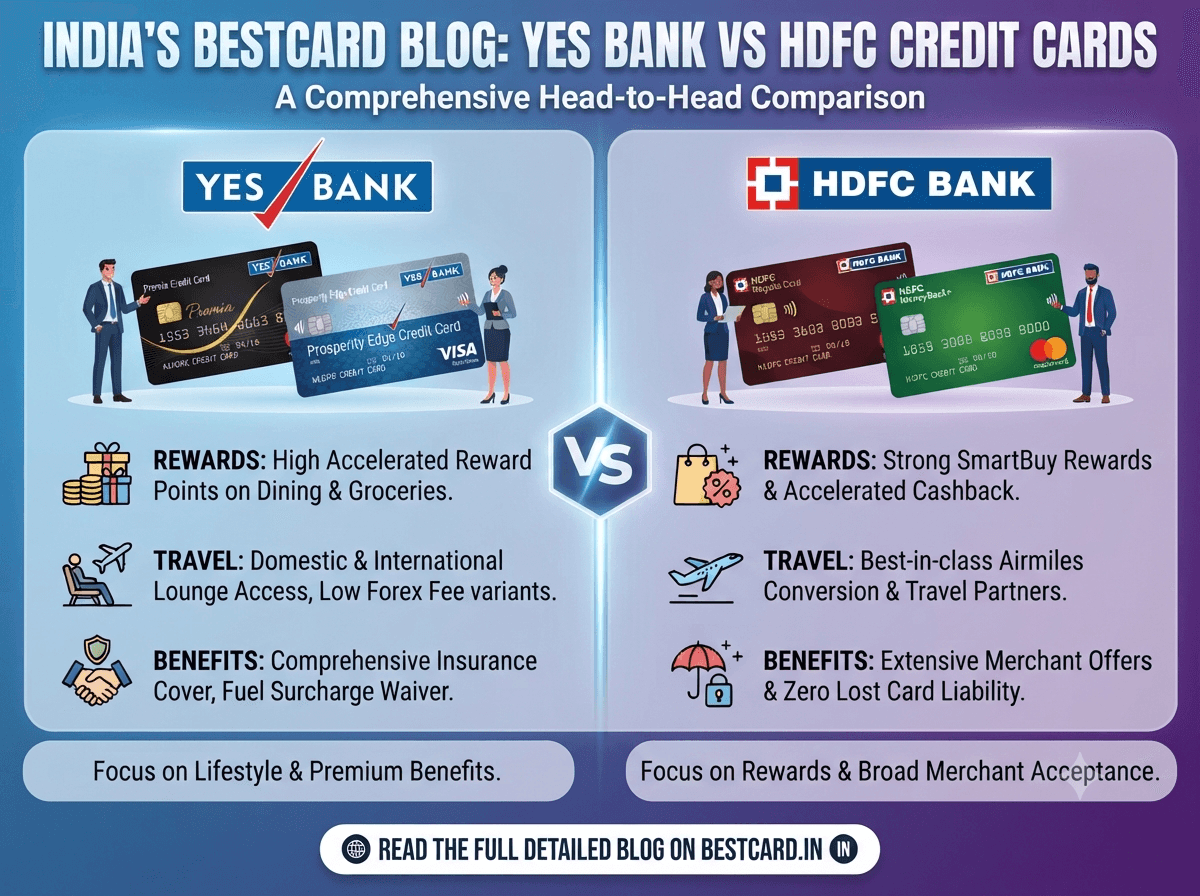
Yes Bank and HDFC sit at very different points on the Indian card market — one an established giant with the widest premium lineup in the country, the other a smaller private bank that's been aggressive on approval criteria and niche rewards to compete for market share.
Approval and eligibility
HDFC's underwriting is conservative and relationship-driven — existing HDFC banking customers get materially better approval odds and pre-approved offers than fresh applicants. Yes Bank has historically been more willing to approve applicants with a shorter credit history or without an existing banking relationship, making it a more accessible starting point if you don't already bank with a major private lender.
Where HDFC wins
HDFC's premium tier, especially cards aimed at frequent travelers and high spenders, remains one of the strongest in the country for lounge access, airline transfer partners, and overall brand trust with merchants for large-ticket EMI conversions. If you're shopping specifically at the premium end, HDFC's lineup is hard to beat.
Where Yes Bank is competitive
Yes Bank has pushed harder on flat-rate rewards and lower eligibility bars for its mid-tier cards, which can suit someone who wants solid everyday cashback without needing a long banking relationship or high income proof to get approved.
The practical takeaway
If you already have an HDFC relationship or a strong income profile, HDFC's tiered lineup gives you room to grow into a premium card over time. If you're earlier in your credit journey or don't bank with either institution yet, Yes Bank's mid-tier cards are worth comparing on pure approval odds.
Where to go from here
Read the full Yes Bank credit cards guide and HDFC credit cards guide for card-by-card detail before applying to either.