
American Express Gold Card Review: Membership Rewards for Patient Point Collectors
3 April 2026 · BestCard Editorial Team
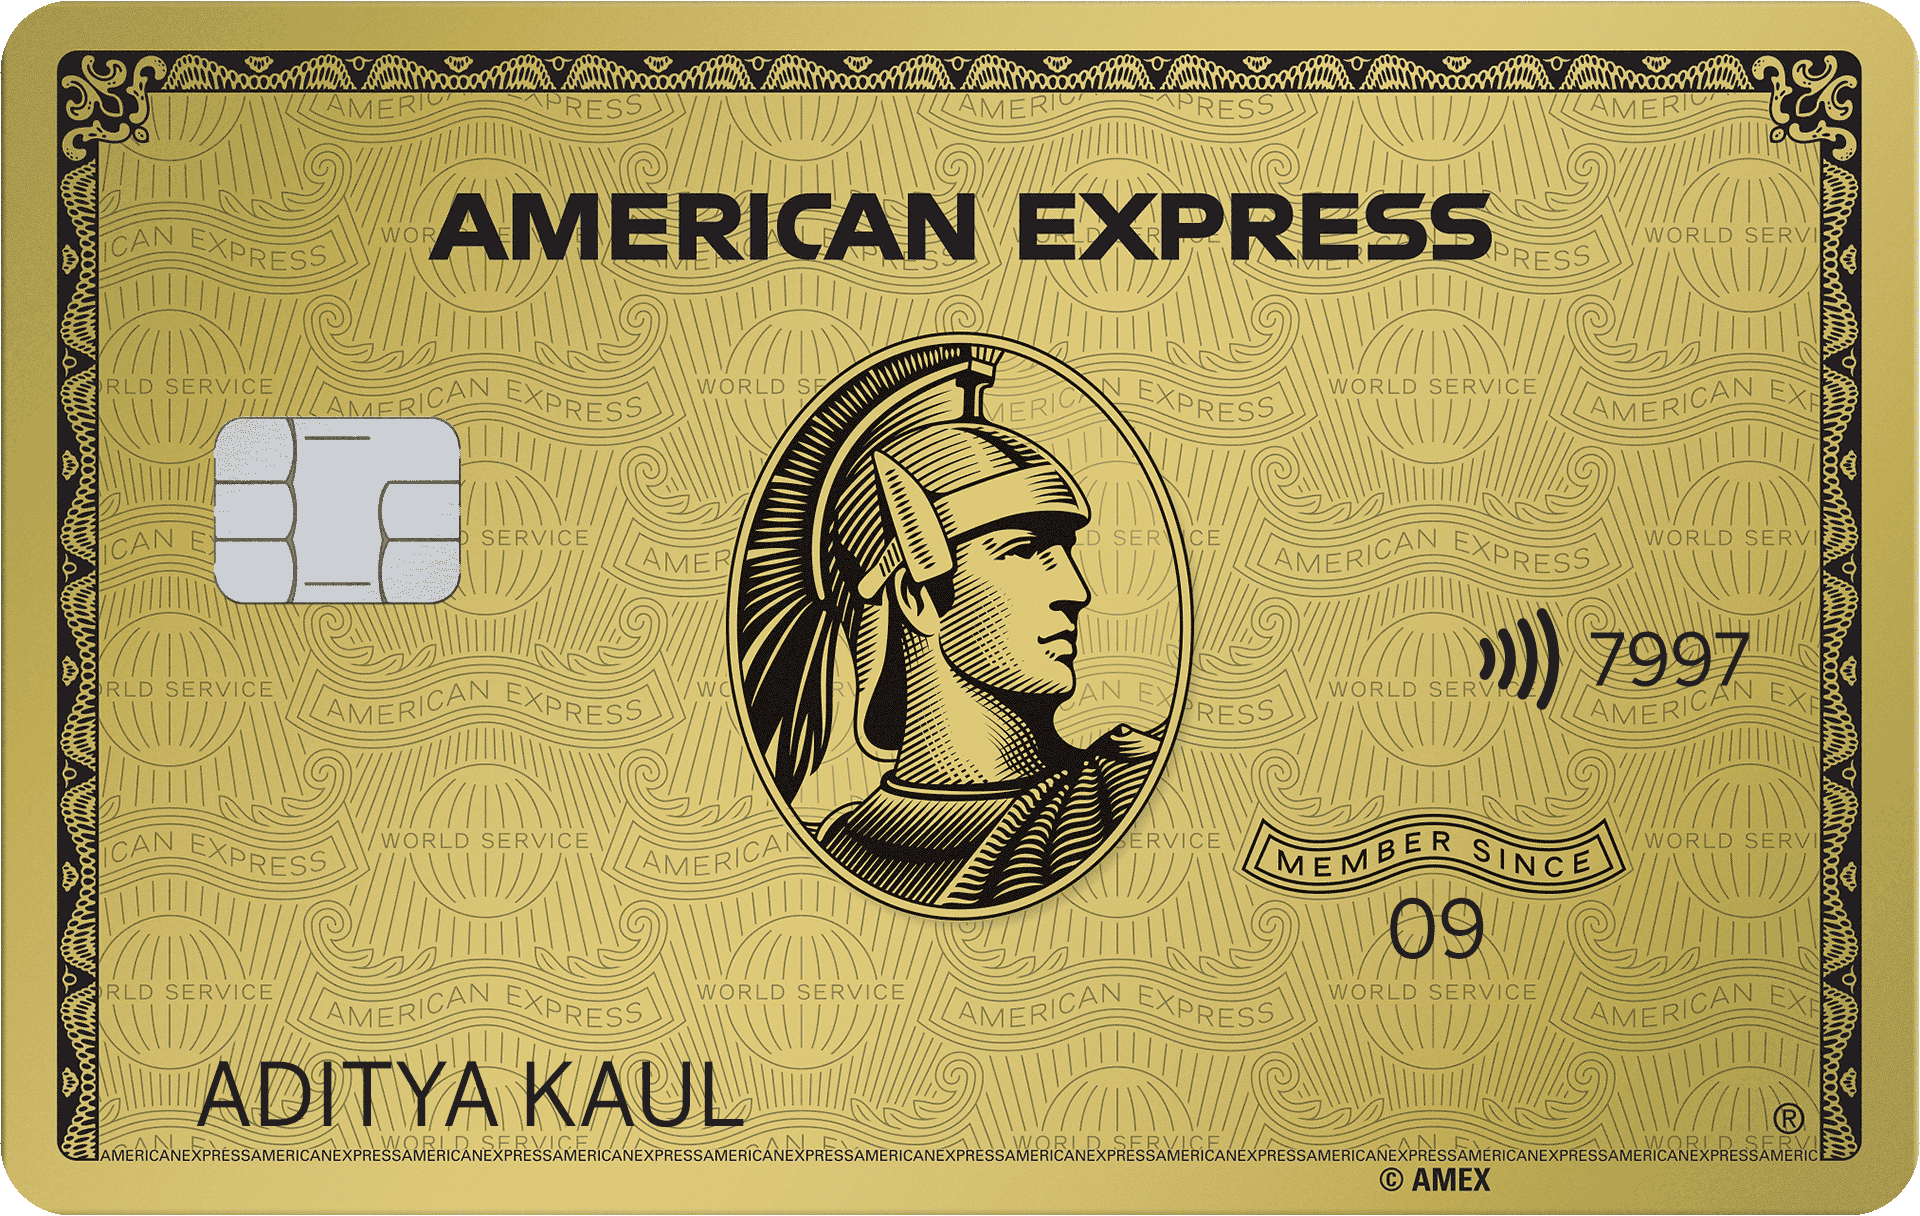
The American Express Gold Card is Amex's classic mid-tier charge card in India, one step below the Platinum Travel. It is built around Membership Rewards, Amex's points programme, and spending milestones rather than a high flat earn rate or a long list of travel perks. For people who already like Amex and plan to transfer points to airline and hotel partners, it has a clear role. For people who want simple cashback, it's usually the wrong card.
Fees and eligibility at a glance
The Gold Card has a ₹1,000 joining fee, and the annual fee from the second year is ₹4,500. That annual fee is the number to plan around. Our data doesn't list a spend-based waiver threshold, so treat the ₹4,500 as a recurring cost the card has to earn back. Amex lists a minimum monthly income of ₹50,000 and a minimum credit score of 750, and the card is open to salaried and self-employed applicants aged 21 to 65. The forex markup is 3.5%.
Rewards and how they actually work
The base earn rate is 1%, with dining and grocery spending earning 2%. Membership Rewards points are valued at around 30 paise each in our data, higher than the 20 paise typical of Axis EDGE points, and Amex's points have two lasting advantages: they never expire, and they can be transferred to airline and hotel loyalty partners at no cost. That makes the Gold Card better suited to slowly building a points balance for a specific trip than to monthly redemptions.
Much of the card's value comes from bonuses rather than the everyday rate. There are bonus Membership Rewards points for reaching a joining-year spend milestone, and further bonus points for crossing annual spend milestones. Our data doesn't list the exact milestone amounts or points awarded, so check the current terms on Amex's page before assuming how much they're worth. In practice, the Gold Card rewards people who deliberately spend up to those milestones.
Lounge access and lifestyle perks
The Gold Card is not a lounge card. We don't list any airport lounge access for it, so if lounges matter to you, look at the Platinum Travel or another card. Its lifestyle side is Amex's usual set of member offers: periodic dining discounts at partner restaurants and partner offers across retail. These vary over time and are nice when they line up with your plans, but they're not something to rely on for guaranteed value.
One practical point: Amex does not offer cash withdrawals on this card. That's rarely a problem, since cash advances on any card are expensive, but it's worth knowing.
What's genuinely good about this card
Points that never expire and transfer to airline and hotel partners for free are the core strength. You can collect slowly and redeem when a good award seat turns up, without worrying about points expiring. Twice the base rate on dining and groceries covers two of the most common household spending categories, and the 30-paise point value lifts the effective return above what the headline percentages suggest. Amex's customer service is also consistently regarded as among the best of any Indian card issuer, which matters when you have a dispute or a charge that needs reversing.
Where it falls short
Acceptance is the biggest everyday problem. Amex is accepted at fewer merchants than Visa, Mastercard or RuPay, particularly at smaller shops and in smaller cities, so you'll need a second card as a backup. A ₹4,500 annual fee with no published waiver is a lot for a 1% base rate. If you don't reach the milestones or transfer points, you're likely to get less back than the fee. There's no lounge access at all, which leaves the Gold Card short on travel perks compared with similarly priced Visa cards. And the 3.5% forex markup makes it an expensive card to use abroad, despite its points being most valuable for travel.
Who this card actually makes sense for
The Gold Card suits someone earning ₹50,000 or more a month who spends heavily on dining and groceries at merchants that accept Amex, can hit the spending milestones without forcing it, and actually transfers points to airline or hotel partners. It works best alongside a Visa or Mastercard for merchants that don't take Amex. If you want lounge access, a low forex fee or plain cashback, a different card will serve you better for the same money.
Where to go from here
For an overview of Amex's full lineup, read the American Express credit cards guide and best Amex credit cards in India. If you want lounges and travel milestones, see the Amex Platinum Travel review, or the Amex SmartEarn review for a cheaper entry point. For advice on using points well, read how to calculate the real value of reward points.
Related reading
- SBI SimplyCLICK Credit Card: A Deep Dive Review
SBI SimplyCLICK is built for online shoppers with a partner-merchant multiplier structure. Here's whether it still holds up against newer cashback cards.
- Tata Neu Infinity Rewards Guide: How NeuCoins Actually Work
How NeuCoins earn and redeem on the Tata Neu Infinity Credit Card, across Tata Neu, BigBasket, Croma, and Westside, and what they're really worth.
- Tata Neu Infinity Credit Card Review: Is It Worth It?
A close look at the Tata Neu Infinity Credit Card's NeuCoin rewards, who it actually suits, and how it compares to a plain cashback card.