Axis Neo Card Review: A Practical First Credit Card
19 January 2026 · BestCard Editorial Team
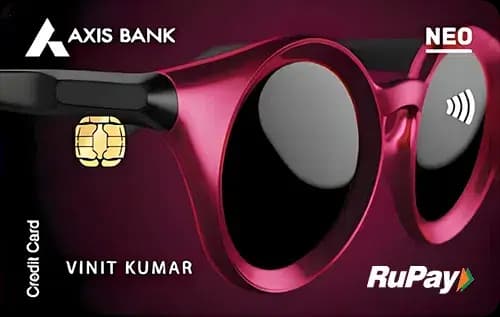
The Axis Bank Neo Credit Card is positioned for people starting out with credit — young professionals, first jobs, or anyone who wants a low-commitment card before stepping up to something bigger. It doesn't try to compete on travel perks or lounge access; instead it leans into everyday categories like dining, groceries, and utility bill payments where a new cardholder's spending actually concentrates.
Who it's for
Neo makes sense if this is your first or second card and your spending is mostly routine — groceries, food delivery, streaming subscriptions, utility bills — rather than travel or large discretionary purchases. If you haven't picked a first card yet, our choosing your first credit card guide is worth reading alongside this review, since it covers what actually matters at this stage (credit-building, low fees) versus what doesn't (premium perks you won't use yet).
Reward structure and earn rate
The base earn rate is modest — 1 EDGE Reward point per ₹200, valued at about 20 paise per point — but it accelerates meaningfully in the categories that matter for a starter card: 10 points per ₹200 on dining and on groceries (each capped monthly, around ₹240 and ₹250 in reward value respectively), and 5 points per ₹200 on utility payments (capped near ₹150). For someone in their first year or two of credit whose spending genuinely sits in these buckets, the effective rate is meaningfully higher than the flat base rate suggests.
There's also a welcome benefit worth noting: 100% cashback up to ₹300, credited automatically on your first utility bill payment within 30 days of getting the card — a small but immediate nudge to start using it for recurring bills.
Key benefits
Beyond the points structure, Neo bundles in ongoing partner discounts that tend to matter more day-to-day than the reward points themselves — Zomato for dining, Blinkit for groceries, BookMyShow for movies, Paytm for bill payments, and Cleartrip for flights and hotels. There's also a 1% fuel surcharge waiver, capped at ₹400 per statement cycle. None of this is flashy, but it's genuinely useful for the spending patterns of someone building credit history rather than optimizing for travel rewards.
Fees
Joining and annual fees are ₹250 each — about as low as a mainstream card gets — which keeps the card easy to justify even in year one while you're still establishing a credit score. For a comparison of how it stacks against other low-fee starter options, see best no annual fee credit cards in India.
How to apply
Neo has a notably open eligibility bar with no strict minimum credit score or income floor listed, just an age requirement of 18–70 — making it accessible for applicants with thin or no credit history. Apply through the Axis Bank credit card application page.
Where to go from here
Once your income and spending grow, it's worth revisiting the Axis Bank credit cards guide to see which card to graduate to next, or comparing entertainment-focused alternatives in the Axis My Zone review. For a broader look at building credit responsibly from a first card, CIBIL score basics is a useful companion read.