
Best Credit Cards for Homemakers in India
15 February 2026 · BestCard Editorial Team
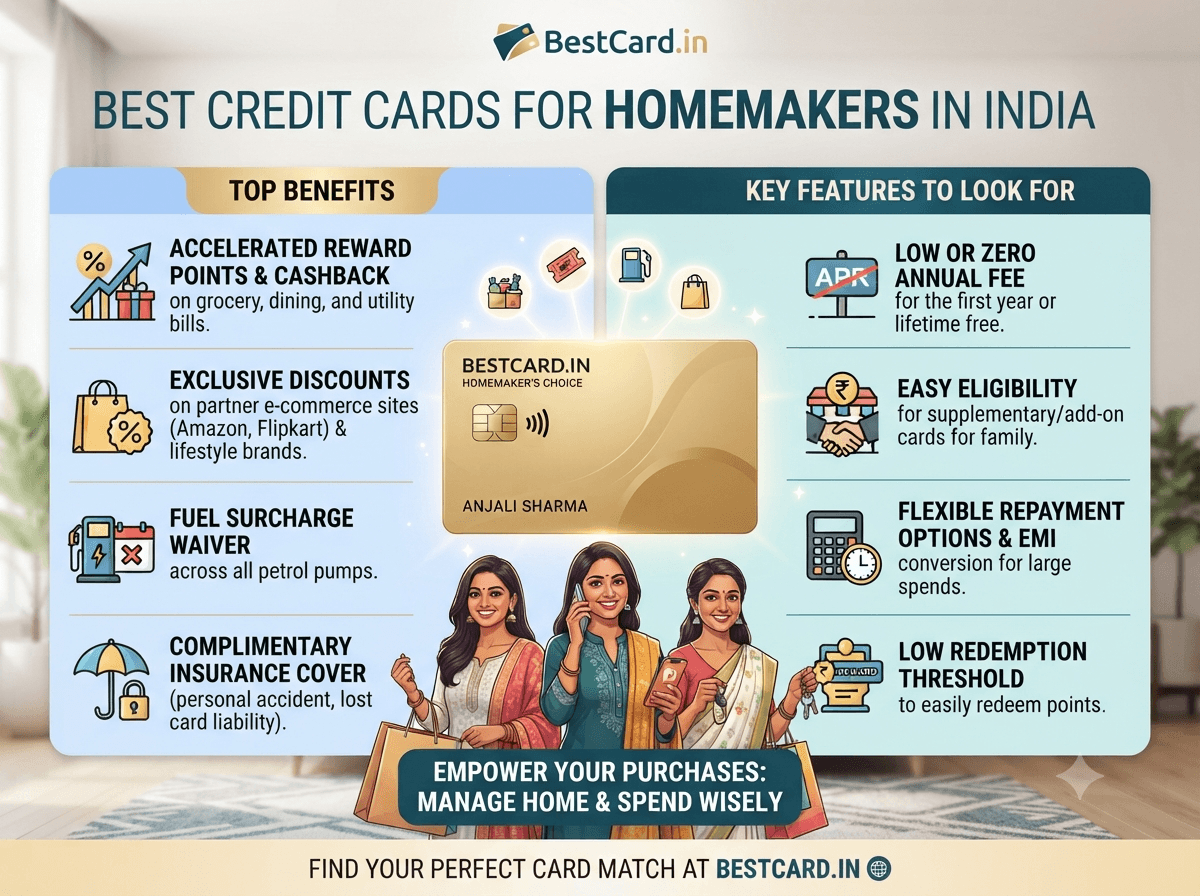
Homemakers without a salary slip are often told they can't get a credit card of their own, which isn't quite true — there are two realistic paths, and both lead to a card that's genuinely useful for running a household.
The add-on card route
The simplest path is an add-on card issued against a working spouse's or family member's primary card account. It carries your own name and card number, builds a limited credit history under your name in some cases, and lets you manage household grocery, utility, and shopping spend directly rather than routing everything through someone else's card. Our add-on credit cards guide covers eligibility and how liability works between primary and add-on holders.
Getting your own primary card
Several banks will issue a primary card against a fixed deposit in your own name — effectively a secured card — even with zero independent income, since the FD itself is the collateral. This route builds your own CIBIL file from scratch, which matters if you want financial independence or plan to apply for a personal loan later using your own credit history rather than a spouse's.
What to actually look for
For household spending, prioritize a card with strong rewards on groceries, utility bill payments, and online shopping over one built for travel or dining — these are the categories that dominate a homemaker's typical spend, and a mismatched card leaves rewards on the table every month.
Cards that fit this spending pattern
The HDFC Millennia is a solid fit for either path above: 2.5% back on groceries and 5% on major online shopping and food-delivery apps, with a ₹1,000 fee waived at ₹1 lakh of annual spend — an easy bar for a household's grocery and utility bills alone. If your spending leans more heavily online than in-store, the SBI Cashback Card pays a flat 5% across all online merchants with no partner restrictions, on a ₹999 fee waived at ₹2 lakh a year.
Where to go from here
Our guide to the best cards for women in India covers issuer-specific options with relevant benefits, and the add-on card guide above is worth reading in full before choosing between the two paths.
Related reading
- Best Credit Cards Under ₹500 Annual Fee in India (2026)
Best credit cards under ₹500 annual fee for 2026: Axis ACE, Flipkart Axis, Swiggy HDFC, SBI SimplyCLICK, IDFC Power+ and Amex SmartEarn, with caps and waivers.
- Lifetime Free vs Paid Credit Card: Which Should You Choose?
Lifetime free or paid credit card? Use a simple break-even formula, real examples from cards like SBI Cashback and Amazon Pay ICICI, and avoid the common traps.
- Dynamic Currency Conversion Explained: Always Pay Local
Dynamic currency conversion explained: why paying in rupees abroad costs more, a worked example, how to spot DCC at terminals and ATMs, and which cards help.