Best Credit Cards With High Reward Rates in India (and What 'High' Actually Means)
29 October 2024 · BestCard Editorial Team
Every bank advertises its best card as earning "5X rewards" or "10% value back" somewhere on the landing page. Almost none of that number survives the fine print. The headline reward rate on an Indian credit card is usually a best-case figure that applies to a narrow spend category, up to a monthly cap that's often a few hundred rupees, using a points-to-rupee conversion that isn't 1:1. If you're picking a card based on the number in the ad, you're picking based on a number you'll rarely actually earn.
What "reward rate" actually measures
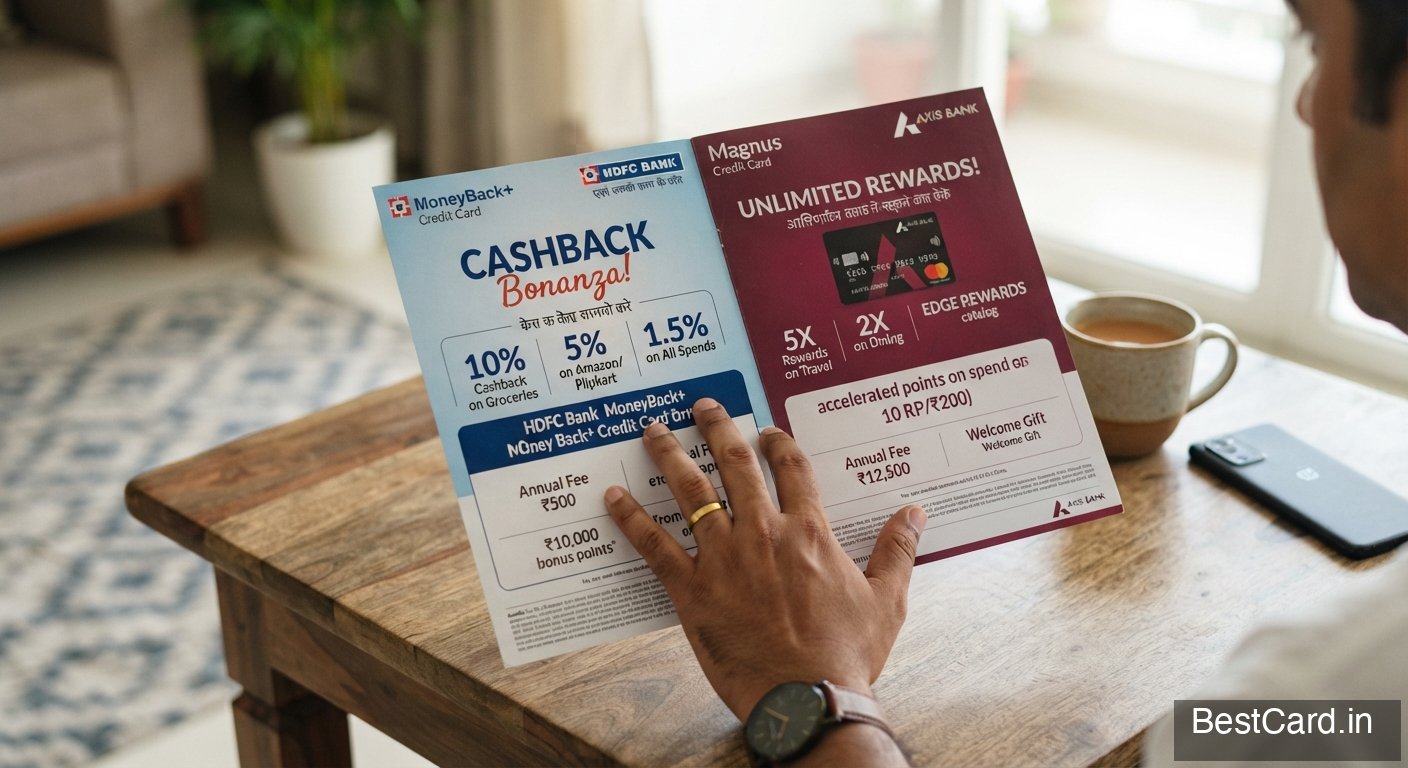
A reward rate is points or cashback earned per ₹100 spent, expressed as a percentage once you convert points back to rupees. The problem is that banks quote the accelerated rate — the one that applies only to specific merchants, specific categories, or specific payment modes — as if it were the card's normal rate. A card that earns 1 point per ₹100 generally but 10 points per ₹100 on a partner airline site will market itself as a "10X rewards card." Outside that airline site, you're earning the base 1X, which after conversion is often worth 0.25-0.5% back, not remotely close to what the ad implies.
Before comparing cards, work out three numbers for each one: the base rate (what you earn on everything else), the accelerated rate (what you earn on the specific bonus category), and the redemption value (what a point is actually worth in rupees when you redeem it — statement credit, vouchers, and travel transfers rarely pay the same). A card's real value to you is a blend of these three, weighted by how much of your spending actually falls into the bonus category.
Where the caps quietly cut into "high" rates
Most high-reward-rate cards cap the accelerated earning at a monthly points ceiling — say, 1,000 or 2,000 bonus points a month on the featured category. Spend past that cap and you drop straight back to the base rate for the rest of the month, with no warning on your statement. If you're a high spender expecting the advertised rate to apply to your full monthly bill, the cap alone can cut your effective reward rate by half or more once you average it out. Always check the cap in absolute rupees, not just the percentage, and compare it against your typical monthly spend in that category.
Exclusions matter just as much. Rent payments, wallet loads, fuel, insurance premiums, government payments, and EMI conversions are commonly excluded from reward earning altogether on cards that otherwise look generous — a category exclusion list buried a few screens deep in the terms is standard practice, not an edge case.
Cards worth comparing for genuinely high reward rates
SBI Card's premium cards run accelerated categories with defined monthly caps that are worth checking against your actual spend pattern rather than the headline multiplier. The Tata Neu Infinity Credit Card earns NeuCoins at a flat, uncapped rate across Tata Neu purchases that's genuinely closer to its advertised number than most co-branded cards, since the accelerated rate isn't confined to a narrow sub-category — see our full Tata Neu Infinity rewards guide for the category-by-category breakdown. Axis Bank cards in the travel and premium segment also carry accelerated rates worth comparing, particularly if the redemption route is travel transfer rather than statement credit, since travel transfers typically hold value better than cash-equivalent redemptions.
Reward rate vs cashback: pick the one that matches how you'll redeem
A high reward-rate card is only worth more than a flat cashback card if you'll actually redeem points at close to their advertised value — which usually means transferring to airline or hotel partners, not converting to statement credit at a marked-down rate. If you're not going to put in that redemption effort, a flat 1-2% cashback card, covered in our rewards vs cashback comparison, will likely outperform a "high reward rate" card in practice. Compare that against our best cashback credit cards roundup before assuming higher headline numbers mean higher real returns.
The real test before applying
Take your last three months of statements, map your spending against the card's bonus categories and caps, and calculate what you'd have actually earned — not what the ad claims. If that number is meaningfully better than a flat cashback card after accounting for redemption friction, the high reward rate is real for you. If it isn't, you're paying attention to marketing rather than math.