Reward Points vs Cashback: Which Credit Card Type Actually Suits You
23 May 2026 · BestCard Editorial Team
This is one of the most common questions when picking a credit card, and there isn't a universally right answer — it depends entirely on how disciplined you are about redeeming rewards and how much effort you're willing to put in for a marginally better return.
The core difference
Cashback is simple: you spend, you get a percentage back, usually as a statement credit. There's no redemption catalog, no expiry to track (in most cases), and the value is exactly what it says — 1% cashback on ₹10,000 spent is ₹100, full stop.
Reward points are more complex. You earn points per rupee spent, and their actual value depends entirely on how you redeem them. Points redeemed for flight tickets or hotel stays through transfer partners can be worth 2-4x their catalog "cash value," while points redeemed for basic merchandise or cash conversion are often worth far less than the headline rate suggests. Our guide to redeeming reward points breaks down exactly where that gap comes from.
Who cashback suits
Cashback is the right call if you want a card and forget about optimizing it. You don't need to research transfer ratios, monitor limited-time transfer bonuses, or figure out which airline's award chart gives the best value. If your spending is broad across categories and you're not booking premium travel with points, a straightforward cashback credit card will almost always out-earn a points card for the same effort level.
Who reward points suit
Points make sense if you travel enough to redeem them for flights or hotels, and if you're willing to spend an hour occasionally researching the best redemption path. A points-heavy card paired with good redemption discipline can regularly return value well above what an equivalent cashback card would pay — this is the appeal behind cards built around lounge access and travel transfers, covered in our travel credit cards guide.
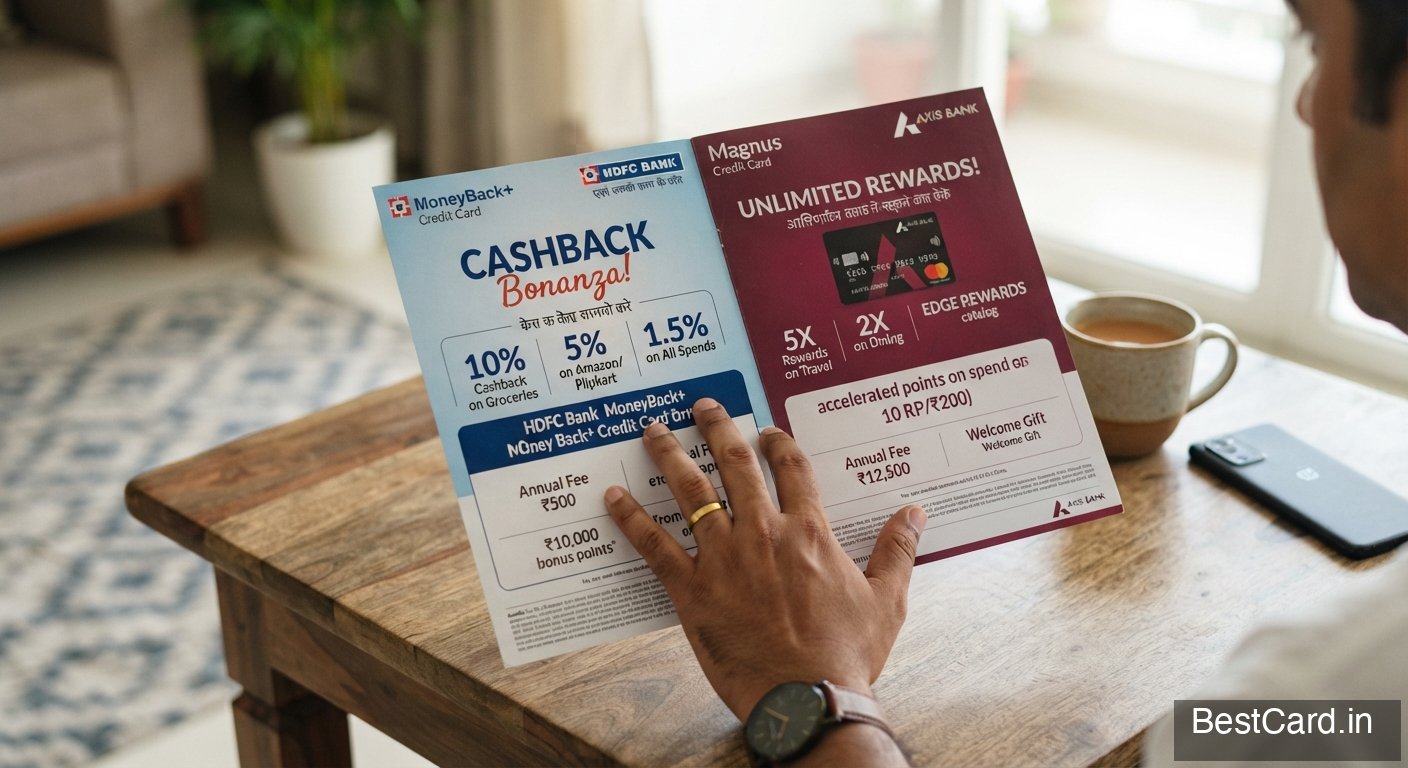
The milestone benefit factor
Many cards, cashback and points-based alike, also carry milestone benefits — bonus rewards for hitting a quarterly or annual spend threshold. These can meaningfully change the real return of a card and are worth factoring into your comparison rather than looking only at the base earn rate. Our milestone benefits guide covers how to actually capture these instead of missing the threshold by a small margin.
Issuer options worth checking
SBI Card offers both cashback-style and points-based cards, so it's worth comparing their specific variants rather than assuming one issuer only does one type. The Tata Neu Infinity Credit Card takes a slightly different approach with NeuCoins that function close to cashback within the Tata ecosystem, which can be a good middle ground if you already shop across Tata brands regularly.
A simple way to decide
If you can honestly say you'll research redemption options a few times a year, go with points. If you know you'll let points sit unredeemed or take the first mediocre option in the catalog, cashback will earn you more in practice even if the headline percentage looks lower. There's no shame in choosing the boring option — unused or poorly redeemed points are worth zero, and a guaranteed 1.5% cashback beats a theoretical 3% points return you never actually capture.
Where to go from here
If you're deciding between your first cashback and points card, our choosing your first credit card guide covers the basics, and once you've picked a direction, check credit card annual fee waivers so the card's fee doesn't quietly eat into whatever you earn.