The Credit Card Checklist to Run Through Before You Fly Out
22 March 2026 · BestCard Editorial Team
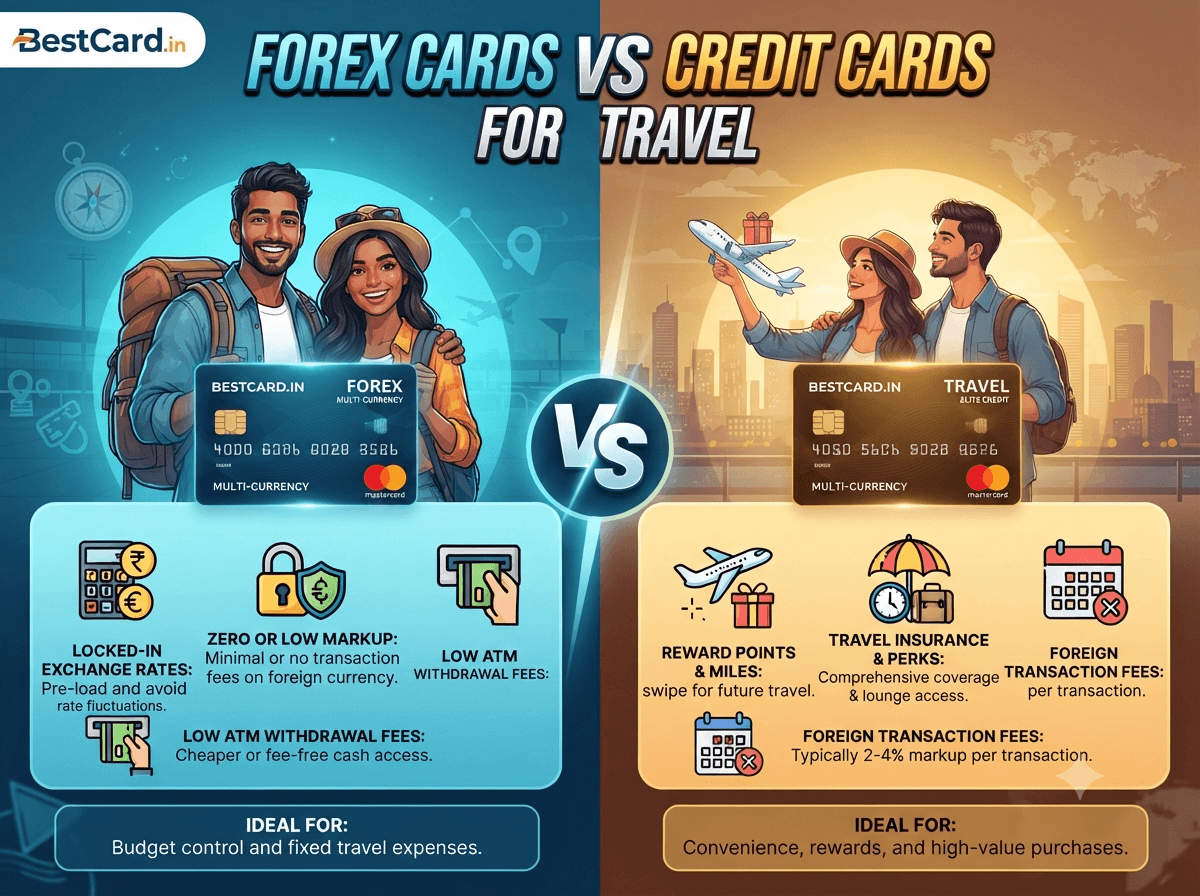
Most credit card problems abroad aren't fraud or theft — they're a transaction declined at a hotel front desk because nobody told the bank you'd left the country, or a forex markup that quietly added 3.5% to every swipe for two weeks. Both are avoidable with a few minutes of setup before you fly. Here's the checklist worth actually running through.
1. Tell your bank you're traveling — even if it says you don't need to
Most Indian issuers no longer require a formal "travel notification" the way they did a decade ago, since fraud systems now factor in geolocation and spending patterns automatically. But automatic systems still flag international activity as higher-risk by default, and a card that's never been swiped outside India before is more likely to get a transaction declined or temporarily frozen on the first attempt abroad. Call your bank or set the travel flag in the app anyway — it's a two-minute step that removes one variable from a trip where you don't want surprises.
2. Check the forex markup on the card you're actually planning to use
Forex markup fees range from as low as 0% to as high as 3.5% depending on the card, and this is usually the single biggest hidden cost of using a credit card abroad. If your everyday card charges the standard 3.5%, that's ₹3,500 in fees alone on a ₹1,00,000 trip — worth carrying a low or zero forex markup card instead, even if it's not your primary card at home. See our full breakdown of how foreign transaction markup fees work and the current best low forex markup credit cards in India if you need to apply for one before the trip — leave at least 2-3 weeks for approval and delivery.
3. Confirm your daily and per-transaction international limits
Indian credit cards typically have separate domestic and international spending limits, and the international limit is sometimes set conservatively low by default, especially on cards you've never used abroad. Check this in the app before you leave — a hotel deposit hold or a jewellery purchase abroad can easily exceed a limit set for casual use. If it's too low, request an increase through the app or by calling the bank; most issuers process this within a day or two.
4. Carry a backup card from a different bank and network
Card networks occasionally have region-specific outages, and a single bank's fraud system can block a card mid-trip based on a false positive with no warning. Carrying a second credit card — ideally on a different network (Visa vs Mastercard) and from a different bank — means one blocked card doesn't strand you. If your primary card is Visa, a Mastercard or RuPay-accepted backup covers more merchant gaps than a second Visa card would.
5. Save your bank's international emergency numbers before you leave, not after
The toll-free number printed on the back of your card usually doesn't work from a foreign SIM or roaming number. Every major Indian issuer publishes a separate collect-call or international emergency number for lost/stolen card reporting — find it on the bank's website and save it in your phone (and write it down somewhere that isn't just your phone) before departure. If a card is lost or compromised abroad, the time between noticing and blocking it is what determines your liability exposure.
6. Decline Dynamic Currency Conversion (DCC) every single time
This is the trap that costs travelers the most without them noticing. When a foreign merchant terminal or ATM asks "would you like to pay in INR instead of local currency," that's DCC — and it almost always applies a worse exchange rate than your card network would, on top of your card's own forex markup. Always choose to be billed in the local currency, never in rupees, even though the terminal will present the INR option as the more convenient-sounding default. This single habit often saves more than switching to a marginally lower forex-markup card would.
7. Set up UPI or a small forex-loaded backup where the trip involves a UPI-linked country
If you're traveling somewhere UPI is now accepted (Singapore, UAE, and a growing list of others), linking a RuPay credit card can bypass forex markup entirely for those transactions. It's not universal yet, so don't rely on it as a primary plan, but it's worth checking before the trip if your destination is on the list.
Putting it together
None of these steps take more than a few minutes individually, but skipping any one of them is what turns a minor inconvenience — a declined swipe, a DCC overcharge, a card you can't report lost — into a real problem mid-trip. Run through all seven before you leave, not after you land.
Where to go from here
For the broader forex-card-versus-credit-card decision, read forex cards vs credit cards for travel. If you're a student heading abroad for an extended stay rather than a short trip, the best credit cards for study abroad students covers the longer-term version of this checklist, and our best credit cards for international travel roundup has specific card picks by travel style.