Marriott Bonvoy HDFC Bank Card Review: A Hotel Co-Brand That Earns Its Fee
2 April 2026 · BestCard Editorial Team
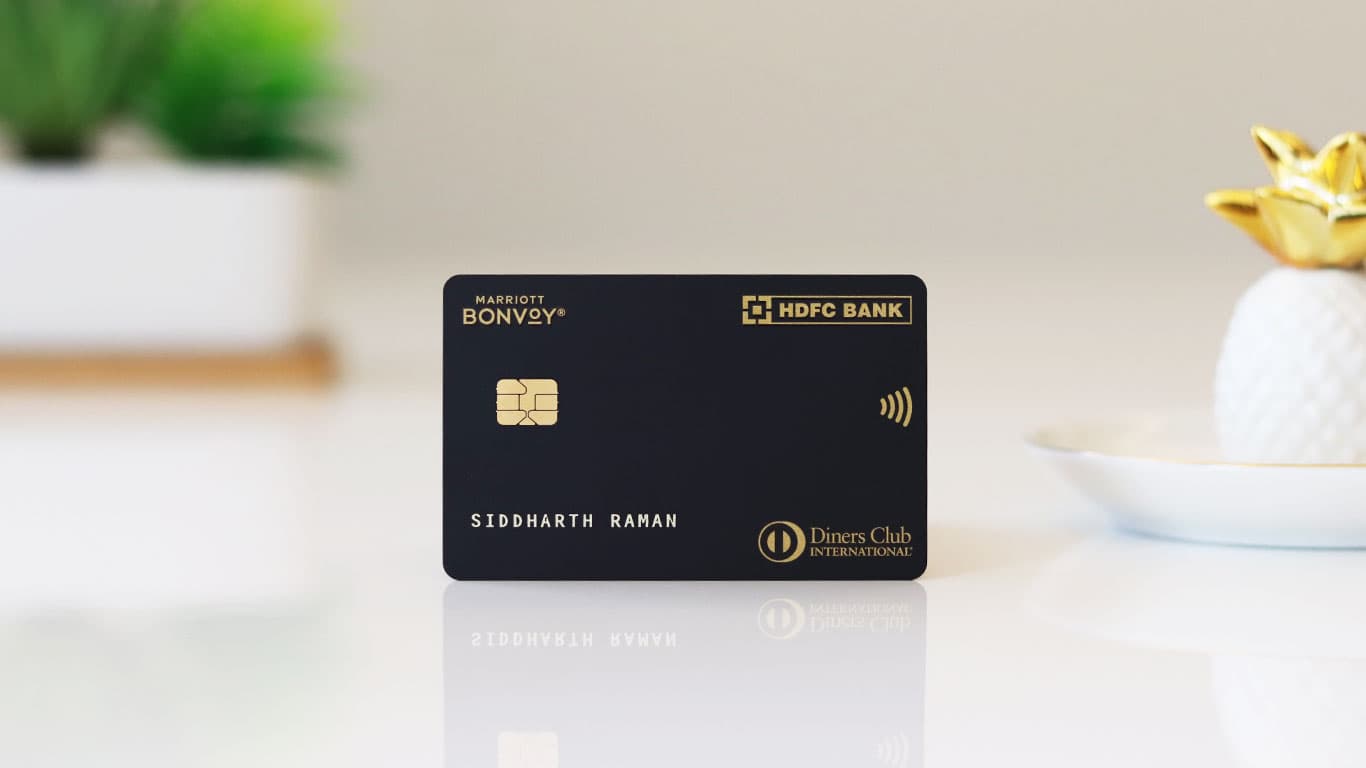
Co-brand hotel cards are usually a bad deal unless you're already loyal to the chain, and the Marriott Bonvoy HDFC Bank Card is a rare exception that's worth a look even if you're only a casual Marriott guest. It's built around Free Night Awards rather than a points-per-rupee race, plus a genuinely generous fixed lounge allowance that has nothing to do with your hotel spending. The honest catch: none of it is spend-waived, so you're paying the fee every year regardless of how much you use the card.
Fees and eligibility at a glance
Joining and annual fees are both ₹3,000. There's no spend-based waiver on this card — HDFC doesn't offer one, so budget for the fee annually rather than expecting it to disappear if you spend enough. The forex markup is 3.5%, in line with HDFC's standard rate rather than the discounted rates you see on dedicated travel cards. Given the fee is fixed and the benefits are fixed too, eligibility here is less about hitting a spend threshold and more about whether you'll actually use what's included.
Rewards and how they actually work
Base earn rate works out to a modest 0.67% in points value — this card isn't designed to be your everyday spender. The real value sits in Free Night Awards: one worth up to 15,000 Marriott Bonvoy points on joining, another on every annual renewal, and three more unlocked at ₹6 lakh, ₹9 lakh, and ₹15 lakh of cumulative annual spend. Travel category spend earns an accelerated 2.67% and dining earns 1.33%, each with modest monthly caps. Redemption for points transfer into the Marriott program is free; catalogue and voucher redemptions can carry a nominal fee.
Lounge access and travel perks
This is where the card quietly overperforms its fee tier: 12 complimentary domestic and 12 complimentary international lounge visits a year — 24 total, and crucially a fixed allowance rather than something gated behind a spend threshold you have to hit first. On top of that, cardholders get complimentary Marriott Bonvoy Silver Elite status plus 10 Elite Night Credits annually, a real head start toward higher elite tiers earned through actual stays. There's also solid international travel insurance (emergency medical cover up to $18,750, air accident cover of $12,500, baggage/document loss cover of $250) and quarterly complimentary golf rounds and lessons.
What's genuinely good about this card
The Free Night Award structure is unusually generous for a ₹3,000 card — getting one just for joining and another every renewal means the card can pay for itself in hotel value alone, before you've earned a single spend-based award. The Silver Elite status plus 10 Elite Night Credits matters if you're building toward Gold or Platinum through paid stays, since those credits stack on top of nights you'd be earning anyway. Twenty-four fixed lounge visits a year is genuinely one of the most generous allowances at this price point — most cards either cap visits much lower or require you to cross a spend threshold first, and this one doesn't. The quarterly golf perks are a nice bonus layered on top rather than the main pitch.
Where it falls short
The absence of any spend-based fee waiver is the clearest limitation — you're paying ₹3,000 every year no matter what, unlike most cards in this range that let heavy spenders use the card for free. The base reward rate of 0.67% is genuinely weak if you plan to use this as a general-purpose card rather than a hotel-and-travel specialist; a dedicated cashback card will out-earn it comfortably on everyday spend. And the value proposition is concentrated almost entirely around actually staying at Marriott properties and using the lounge visits — if you don't do either, the ₹3,000 fee buys you very little.
Who this card actually makes sense for
This card is for someone who stays at Marriott properties at least a few times a year, values elite status progression, and will actually use two lounge visits a month rather than let them expire unused. If Marriott isn't part of your regular travel pattern, the fixed fee with no waiver makes it a harder sell than a general travel card with a spend-based waiver option.
Where to go from here
For HDFC's broader card lineup and where this one fits, see the HDFC credit cards guide. If lounge access is the main draw, compare it against best credit cards for airport lounge access 2026, and the HDFC Regalia review is a useful comparison if you want lounge access without committing to the Marriott ecosystem specifically.