Best Zero and Low Forex Markup Credit Cards in India: 2026 Update
19 August 2026 · BestCard Editorial Team
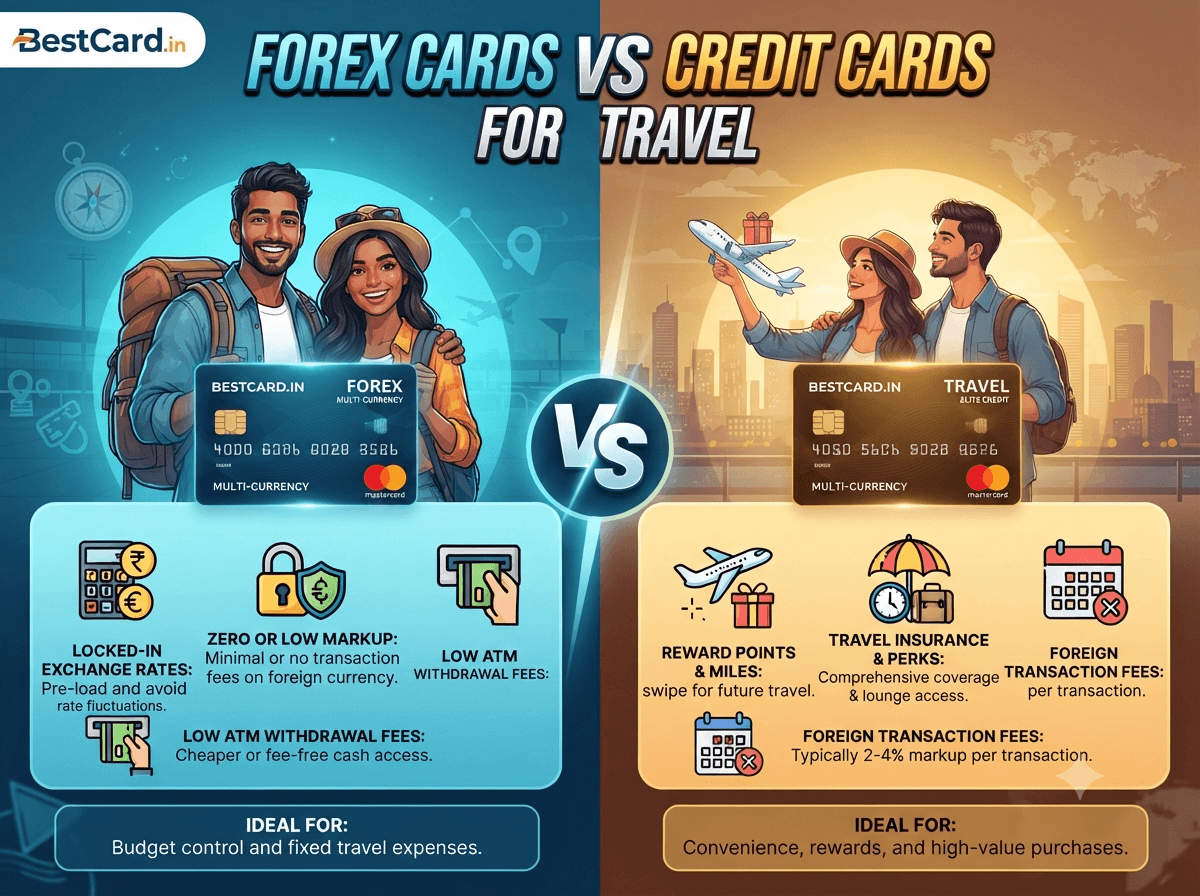
The zero and low forex markup card space has shifted enough this year that it's worth a fresh look rather than assuming last year's picks still hold. More issuers have entered the category, a couple of previously strong cards have quietly repriced their markup or added eligibility restrictions, and the DCC problem that erodes savings on any of these cards hasn't gone away.
What's actually changed
The biggest shift is that zero or near-zero forex markup has moved from a niche premium-card feature to something available on more mid-tier and even some lifetime-free cards, which is good news for travelers who don't want to carry a high-annual-fee card just for the forex benefit. At the same time, a few issuers have tightened the fine print — some "zero forex markup" cards now apply that rate only to spends above a monthly threshold, or only on specific merchant categories, reverting to the standard 3.5% below the threshold. The headline "0% forex markup" claim is worth checking against current terms rather than trusting the name of the card alone, since this is exactly where issuers have been making changes.
RuPay-UPI international acceptance has also expanded to more countries this year, which matters for this topic specifically because UPI-linked RuPay credit card transactions in supported countries bypass forex markup structures altogether — a genuinely different mechanism from a low-markup Visa or Mastercard swipe, and worth using where available even alongside a low-forex card as backup.
Current best picks
Cards that maintain a genuinely low or zero forex markup across all international spend, without a spend-threshold catch, remain the right default recommendation for frequent travelers. The detailed, regularly updated comparison of specific cards, fees, and eligibility sits in our best low forex markup credit cards in India guide — that's the one to check for exact current rates and issuer terms, since those numbers move often enough that repeating them here would go stale quickly. The general shift worth noting for 2026 specifically is that it's now realistic to get a genuinely low-markup card without also paying a steep annual fee, which wasn't reliably true a couple of years ago.
For cardholders who travel internationally often enough to justify it, a premium travel card with a zero markup plus lounge access and travel insurance built in can be a better overall value than optimizing forex markup alone — see best credit cards for international travel if lounge access and insurance matter as much as the markup rate for your travel pattern.
Why DCC awareness matters more, not less, this year
Even as forex markup rates on cards improve, Dynamic Currency Conversion at the point of sale remains untouched by any of these changes — it's a merchant-terminal-level trick, not a card-level fee, so a 0% markup card gains you nothing if you accept DCC's worse exchange rate at checkout. If anything, DCC prompts have become more aggressive and more common as more merchants worldwide adopt payment terminals that default to offering it, precisely because it's profitable for the acquiring bank and merchant, not for the cardholder. Always choose to be billed in the local currency, never in rupees, regardless of how good your card's forex markup is — this single habit protects more value than chasing the last 0.5% of markup difference between two cards.
The practical 2026 approach
Check your current card's actual forex markup terms rather than assuming they haven't changed since you last looked — issuers do adjust these. If your card charges the standard 3.5% and you travel internationally more than occasionally, applying for a genuinely zero-markup card is worth the effort this year, given how many more options now exist without also requiring a steep annual fee. And regardless of which card you carry, decline DCC every time and use RuPay-UPI where your destination supports it as a markup-free supplement to your card.
Where to go from here
For the mechanics behind forex markup fees generally, read how foreign transaction markup fees actually work and forex cards vs credit cards for travel. Before your next trip, run through our credit card international travel checklist, which covers DCC and the rest of the pre-departure setup in full.