How to Pick Your Second Credit Card
22 October 2024 · BestCard Editorial Team
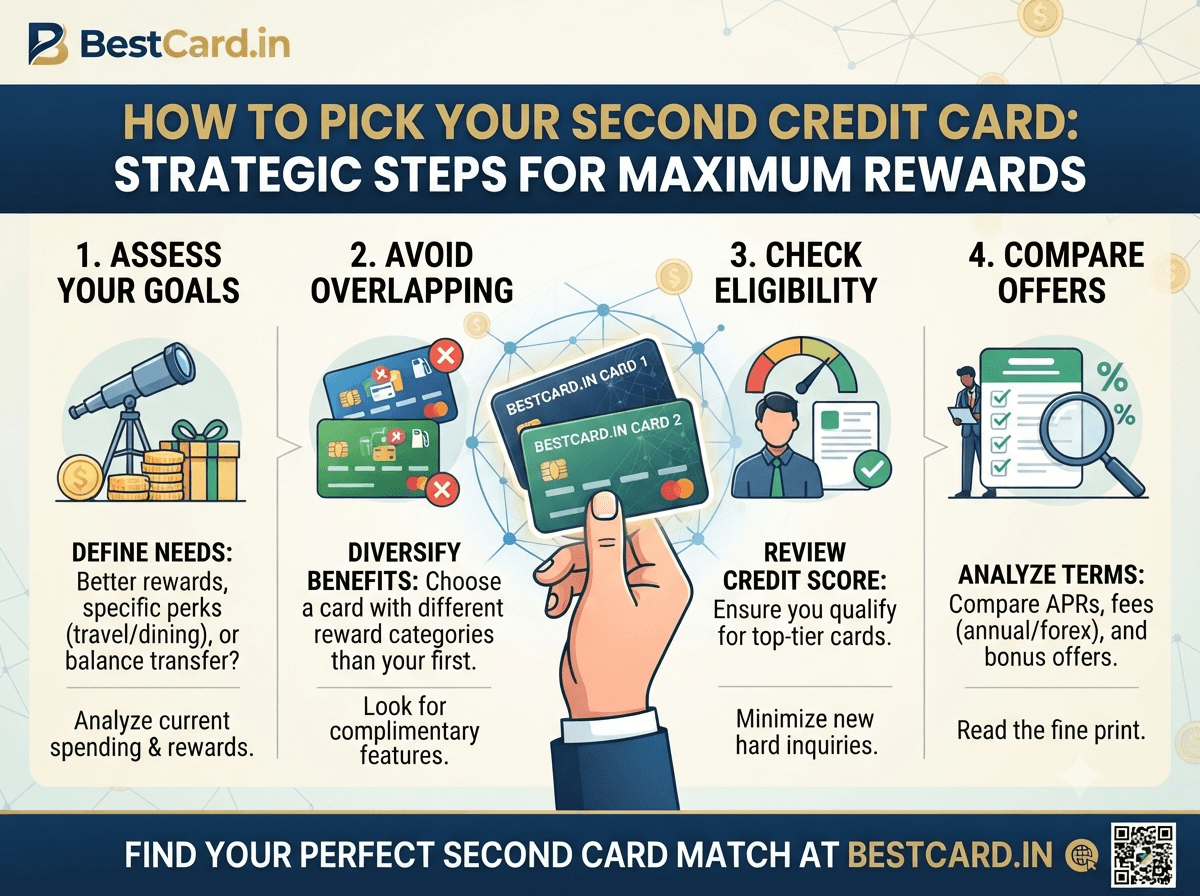
Once you've had a first credit card for a year or so, the question of a second one usually comes up — but a second card is only worth getting if it fills a gap your first card leaves open, not just because you can qualify for one.
Start by mapping what your first card doesn't reward well
Pull up your last three or four statements and sort spending by category. If your first card is a general cashback card and you're spending heavily on fuel, dining, or travel that it doesn't specifically reward, that's your gap — a category-specific second card can meaningfully out-earn adding more spend to the general card.
Consider issuer diversification too
Beyond reward categories, having your second card from a different bank than your first gives you a backup if one issuer ever restricts, flags, or has an outage on your account — not a common event, but not rare enough to ignore either. Tata Neu Infinity Credit Card or SBI Card paired with a different issuer's travel or fuel card is a common combination that covers both diversification and category gaps at once.
Don't chase a second card just for a welcome bonus
Welcome bonuses are real value, but they're a one-time event — the card's actual reward structure for the following years matters more for a card you'll hold long-term. If the ongoing rewards on a prospective second card aren't meaningfully better than your first for the category you're targeting, the welcome bonus alone isn't a strong enough reason.
Where to go from here
Read how many credit cards should you have for the broader question of when to stop adding cards, and choosing a card based on monthly expenses for the category-mapping exercise in more depth.