
YES Bank ELITE+ Credit Card Review: Modest Rewards, Generous Lounges for ₹999
1 April 2026 · BestCard Editorial Team
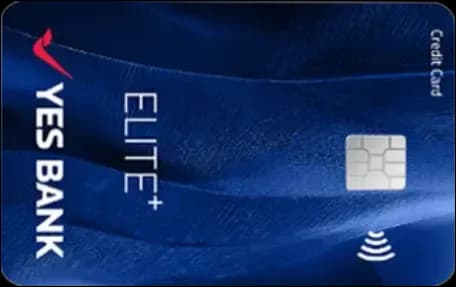
The YES Bank ELITE+ Credit Card is a mid-tier all-rounder. It earns a decent rate on online shopping, a weak rate everywhere else, and packs in more lounge access than you'd expect for a ₹999 fee. It also has a forex markup below the usual 3.5%. None of its features is best in class, but together they make a reasonable card for someone who shops online, flies a few times a year and doesn't want to pay a premium fee. If rewards are your main goal, cheaper cards earn more.
Fees and eligibility at a glance
ELITE+ charges a ₹999 joining fee and a ₹999 annual fee, and the annual fee is waived on ₹2 lakh of yearly spend. That's about ₹16,700 a month, which is achievable but not automatic, and higher than the ₹1 lakh bar many entry cards set. Eligibility asks for a credit score of 700, a minimum monthly income of ₹25,000 and an age between 21 and 60, for salaried and self-employed applicants. It runs on Visa, the forex markup is 2.75%, and interest on revolving balances is 3.5% a month.
Rewards and how they actually work
ELITE+ earns reward points worth about 25 paise each. Online shopping is the strongest category, at an effective 1.5%. Dining and travel earn about 0.75%, and the rest of your offline spending about 0.5%. So the card rewards where you shop as much as how much you spend.
Here's a realistic month. Put ₹15,000 on the card, with ₹6,000 online, ₹3,000 on dining and ₹6,000 on other spends. You'd earn about ₹90 from online shopping, ₹22 from dining and ₹30 from the rest, roughly ₹140 a month or ₹1,700 a year. At ₹15,000 a month you'd also fall just short of the ₹2 lakh waiver and pay the ₹999 fee, leaving around ₹700 in net rewards. Push monthly spend to ₹17,000 and the fee disappears, which makes a real difference to the card's value.
Lounges, forex and other perks
Lounge access is the main reason to look at ELITE+. The primary cardholder gets 2 complimentary domestic lounge visits per quarter, 8 a year, plus 3 complimentary international lounge visits a year. For a ₹999 card, that's a generous allowance, enough for four domestic round trips and an international holiday.
The 2.75% forex markup is below the 3.5% common on entry and mid-tier cards. On ₹1 lakh of overseas spending, you'd pay ₹2,750 in markup instead of ₹3,500, a saving of ₹750. That's helpful but not dramatic. Dedicated low-forex cards do much better.
There's also a golf privilege programme at select courses in India, movie ticket discounts, and a 1% fuel surcharge waiver on transactions between ₹400 and ₹5,000, capped per statement cycle. The golf and movie perks only matter if you go out of your way to use them.
How it compares with HDFC Millennia and SBI SimplyCLICK
The HDFC Millennia review covers the obvious online-shopping alternative. Millennia costs ₹1,000, waived on ₹1 lakh of spend, and pays 5% on a list of major online merchants (capped at ₹1,000 a month), 2.5% on groceries and 1% on most other spends. On that same ₹6,000 of online spend, Millennia earns about ₹300 against ELITE+'s ₹90. But Millennia's forex markup is 3.5%, and its lounge perk is a single quarterly voucher unlocked only after ₹1 lakh of spend in that quarter. Millennia wins clearly on rewards. ELITE+ wins on lounges and forex.
The SBI SimplyCLICK review covers the budget option. SimplyCLICK costs ₹499, waived on ₹1 lakh, earns about 2.5% on partner online merchants and adds a ₹500 Amazon voucher on joining. It has no lounge access, a 3.5% forex markup, and a lower income bar of ₹20,000 a month. If you never use airport lounges, SimplyCLICK earns more for less.
What's genuinely good about this card
Eight domestic and three international lounge visits a year is a lot for ₹999, and they come with no spend condition attached. The 2.75% forex markup is better than most cards at this level. The 1.5% online rate is reasonable, and the ₹25,000 income requirement keeps the card accessible. As a single card that covers online shopping, occasional travel and the odd overseas purchase, it does a little of everything.
Where it falls short
Offline spending earns between 0.5% and 0.75%, which is weak for groceries, fuel and everyday bills. The ₹2 lakh fee waiver is double what many competing cards require. The online rate, while decent, is well behind dedicated online-shopping cards. And the golf and movie perks only add value if you actively use them.
Who this card actually makes sense for
ELITE+ suits a salaried professional who flies domestically several times a year, takes the occasional international trip, does a good share of shopping online and can put about ₹17,000 a month on the card to keep the fee waived. For that person, the lounge visits alone justify the card. If you rarely fly, a cashback card like Millennia will earn you more.
Where to go from here
For the rest of YES Bank's range, see the YES Bank credit cards guide and our YES Bank Marquee review for the bank's flagship. If online shopping is your main spend, the best credit cards for online shopping roundup is a useful comparison, and our guide to credit card annual fee waivers explains how to make sure you hit the ₹2 lakh target.
Related reading
- American Express Gold Card Review: Membership Rewards for Patient Point Collectors
A grounded review of the American Express Gold Card in India: Membership Rewards points that never expire, 2% on dining and groceries, milestone bonuses, and the fee and acceptance trade-offs.
- ICICI Bank Expressions Credit Card Review: Pick the Design, Then Check the Maths
An honest review of the ICICI Bank Expressions card: 175+ card designs, 3 points per ₹100 worth about 0.75%, spend-gated lounge and golf perks, and how it stacks up against ICICI Coral and Amazon Pay.
- Axis Bank Rewards Credit Card Review: A Grocery Starter Card That's Hard to Recommend
An honest review of the Axis Bank Rewards Credit Card: 1% value on groceries, 0.5% elsewhere, a ₹500 fee waived at ₹1.5 lakh, and why Axis's own ACE and My Zone often do the job better.