Didn't Get Your Credit Card Statement? Here's What to Do
14 August 2026 · BestCard Editorial Team
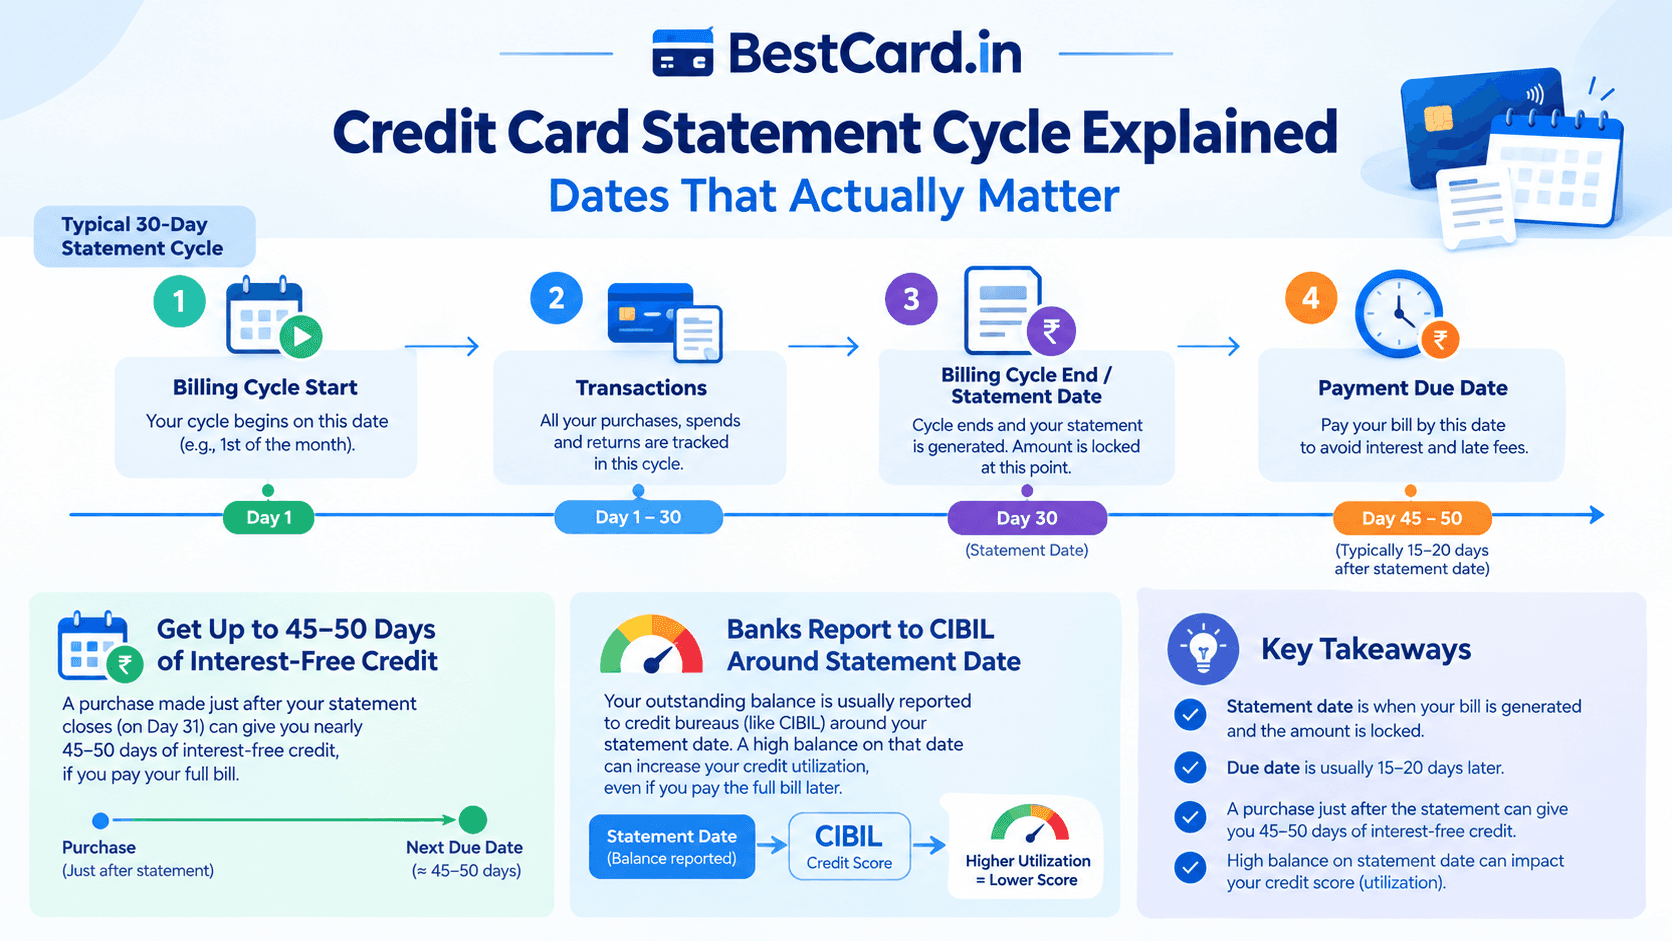
Not receiving your statement doesn't pause your due date — that's the single most important thing to understand before anything else here. Your billing cycle runs on a fixed schedule regardless of whether the statement notification actually reaches you, so a missing statement is a problem to solve immediately, not something to wait out.
First, confirm the statement actually wasn't generated
Before assuming there's a delivery problem, log into your issuer's net banking portal or mobile app and check directly — most banks generate the statement on schedule even when the email or SMS notification fails, so the fastest fix is often just viewing it directly in-app rather than waiting for a notification. Our guide to reading a credit card statement is useful once you've located it, to confirm you're looking at the current cycle and not an old one. If the statement genuinely isn't available anywhere in the app either, move to the checks below.
Common reasons statements go missing
- Email delivery issues — the statement email landed in spam or promotions, your registered email has a full inbox, or your issuer's email is being filtered by your provider
- Outdated contact details — you changed your email or phone number and never updated it with the bank, so notifications are going to an old address entirely
- App or SMS notification failures — a temporary technical issue on the issuer's end, more common right after an app update or a bank system migration
- Physical statement opted out — if you'd switched to paperless statements at some point and then also stopped seeing digital ones, there may be no fallback channel active on your account at all
- New card or recent reissue — a freshly issued or replaced card sometimes has a short window where statement generation or delivery preferences haven't fully synced
What to do immediately
- Check net banking and the app directly rather than relying on notifications — this is the fastest path to your actual due amount and due date.
- Call customer care if the statement isn't visible anywhere, and ask them to confirm your current outstanding balance and due date verbally, then get it confirmed in writing via email or SMS if possible.
- Update your registered email and phone number immediately if you suspect they're outdated — this is the root cause in a large share of these cases and it's worth fixing permanently, not just for this cycle.
- Pay based on the confirmed amount, even without the formal statement in hand — do not wait for the PDF to arrive if the due date is close, since paying late because the statement was delayed still results in the same late fee and CIBIL impact as any other missed payment. Our credit card late payment consequences guide covers exactly what's at stake if this slips.

Can you get a late fee waived if the statement never arrived?
Sometimes, but don't count on it. Most issuers will consider waiving a late fee if you can show the statement genuinely wasn't delivered and you paid promptly once you discovered the issue, especially if it's a first-time occurrence on the account. This isn't guaranteed, though — banks generally expect cardholders to track their due date independently rather than relying solely on notifications, so a waiver request works better when paired with proof you acted quickly once you noticed the gap, not as a standing excuse. Understanding your billing cycle mechanics well enough to estimate your due date even without a statement is the best insurance against this ever costing you money.
Preventing this going forward
Set a recurring calendar reminder a few days before your typical due date, independent of any bank notification — this is the single most reliable fix, since it doesn't depend on the bank's delivery systems working correctly every month. Enable multiple notification channels if your issuer supports it — email plus SMS plus app push — so a failure in one channel doesn't leave you fully blind. And if you've recently changed your phone number, email, or address, update it across every card you hold immediately rather than assuming one bank update covers all your accounts, since each issuer maintains contact details independently.
If you use autopay or standing instructions for your credit card bill, a missing statement is less risky since the payment happens regardless — but confirm the autopay amount matches what you actually owe, since our credit card auto-debit failure charges guide covers what happens when an autopay attempt fails, which is its own separate risk worth understanding.
Where to go from here
Read credit card payment due date vs billing date to understand the mechanics well enough to estimate your due date independently, and what happens if you skip a payment entirely if a missing statement has already caused you to miss a cycle completely.