
Credit Card Autopay and E-Mandates: A Complete 2026 Guide
2 October 2026 · BestCard Editorial Team
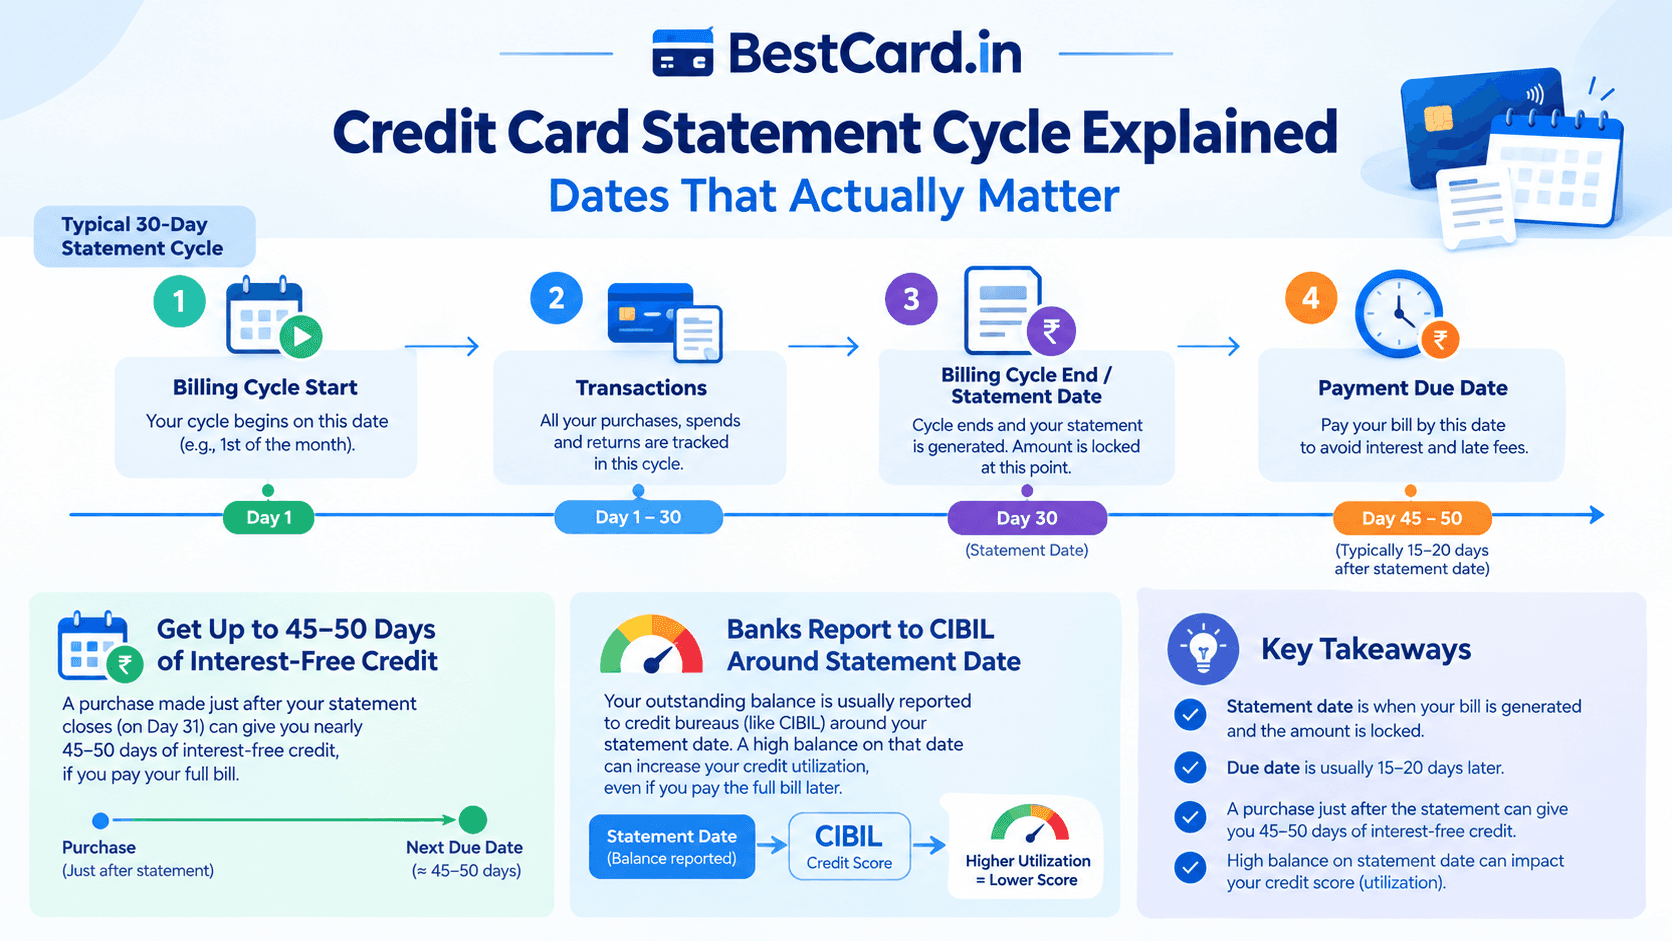
Credit card autopay comes in two forms: e-mandates that let merchants charge your card on a schedule, and standing instructions that pay your card bill from your bank account. Set both up properly and you never miss a due date or a subscription renewal. Set them up carelessly and you end up with forgotten subscriptions, failed debits and interest you never planned for.
This guide covers how each one works under RBI's rules, how to set them up and cancel them, and how to earn rewards on recurring bills.
Two kinds of autopay, and why the difference matters
Autopay on your card (merchant e-mandate). You let Netflix, an insurer, a broadband provider or an electricity board charge your credit card every month. The money leaves your card's credit limit and shows up on your statement like any other purchase.
Autopay for your card bill (bank standing instruction). You tell your bank account to pay your credit card's dues on or before the due date, usually through the card issuer's own auto-debit facility or a NACH mandate. Here the money leaves your savings account.
Most people need both. The first keeps your subscriptions running and earns rewards on them. The second makes sure that pile of recurring charges gets paid on time.
How RBI's e-mandate rules work
RBI's framework for recurring card payments has a few fixed principles that every bank follows:
- One-time registration with authentication. When you first set up a mandate, you authenticate with an OTP or similar. You choose or accept a maximum amount and a frequency.
- Pre-debit notification. Before each recurring debit, your bank must notify you (usually by SMS or email) at least 24 hours in advance, with the merchant name, amount and date. You can opt out of that specific debit from the link in the alert.
- Authentication-free limit. Recurring debits up to a set per-transaction limit go through without a fresh OTP. RBI has set ₹15,000 as the general limit, with a higher limit of ₹1 lakh for certain categories such as insurance premiums, mutual fund subscriptions and credit card bill payments. Debits above the limit need fresh authentication each time.
- You can withdraw at any time. Every mandate must be cancellable through your bank, without needing the merchant's cooperation.
RBI revises these limits from time to time, so check your bank's current page or RBI's notifications for the latest numbers before relying on them for large payments.
Setting up a merchant e-mandate on your card
- At checkout, choose "card" and tick the option to save the card or enable autopay. The merchant will ask for a mandate amount (sometimes a cap higher than your actual bill, to cover price changes).
- Authenticate with the OTP from your issuer.
- Look for a confirmation SMS from your bank with a mandate ID. Keep it; you will need it if a dispute arises.
- Check your card app's "standing instructions" or "manage mandates" section to confirm it appears.
A few practical tips. Set the cap close to the real bill so a surprise price hike triggers an OTP instead of a silent charge. Use one card for all your recurring payments so there is one place to audit them. And if your card is replaced after a loss or expiry, your mandates may need to be registered again, so expect a few failed debits after a card change.
Setting up autopay for your credit card bill
This is the more important of the two, because a missed card payment costs you late fees, interest and CIBIL damage. Every major issuer lets you set up auto-debit from a savings account, usually from net banking or the card app. You pick between:
- Total amount due. The whole statement balance is paid on the due date. No interest, no late fee. This is the right choice for almost everyone.
- Minimum amount due. Only the minimum is paid. You avoid the late fee, but interest accrues on the unpaid balance and on new purchases. Our minimum due trap explainer shows how quickly that adds up.
- Fixed amount. Rarely useful, since your bill changes every month.
If your card and savings account are with the same bank, auto-debit is usually instant to set up. For a card from a different bank, the issuer will register a NACH mandate on your account, which can take a cycle or two to activate. Pay manually until you see confirmation that the mandate is live.
Keep enough balance in the linked account a day or two before the due date. A failed auto-debit can attract a bounce charge from your bank and a late payment charge from your card issuer, and it still counts as a missed payment. Our guide to due date vs billing date explains the timing in detail.
Earning rewards on recurring bills
Recurring payments are predictable spend, so it pays to route them through a card that rewards that category. A few cards in BestCard's data are built for exactly this:
| Card | Annual fee | Recurring-bill benefit | Cap |
|---|---|---|---|
| HSBC Live+ | ₹999 | 10% cashback on utilities | ₹1,000 a month |
| Axis ACE | ₹499 | 5% cashback on bill payments via Google Pay | ₹500 a month |
| Axis Bank Airtel | ₹500 | 25% cashback on Airtel bills and recharges | ₹250 a month |
| Tata Neu Infinity HDFC | ₹1,499 | 5% on utilities via Tata Neu | Check issuer terms |
Here is the maths on a typical month. Say your electricity, broadband and mobile bills total ₹6,000. On HSBC Live+, 10% of ₹6,000 is ₹600, well under the ₹1,000 monthly cap, so you keep all of it: ₹7,200 a year. On Axis ACE paid through Google Pay, 5% of ₹6,000 is ₹300, within the ₹500 cap: ₹3,600 a year against a ₹499 fee. If your bills go through Tata Neu, the Tata Neu Infinity card gives 5% back as NeuCoins.
Two caveats. Many issuers now exclude or cap rewards on utility, insurance and government payments, and some charge a fee on utility spends above a monthly threshold. See our explainer on utility and education transaction fees before moving large bills onto a card. And figures here reflect BestCard's latest card data, but issuers change terms often, so verify on the issuer's site before applying. For a wider shortlist, see best credit cards for utility bill payments.
How to audit and cancel mandates
Do this once a quarter. It takes ten minutes and usually finds at least one subscription you forgot about.
- Open your card app or net banking and find the section for standing instructions, e-mandates or recurring payments. Some banks route this through a separate mandate hub linked from their site.
- List every active mandate with its merchant, cap and frequency.
- Cancel anything you no longer use. Cancelling at the bank stops future debits even if the merchant ignores your cancellation request.
- Also cancel inside the merchant's app, so the service doesn't keep retrying the charge and sending you failure emails.
If a merchant charges you after you cancelled, raise a dispute with your issuer using the mandate cancellation reference. Our chargeback vs refund guide explains how that process works.
Common mistakes to avoid
- Setting your own card bill on minimum due "just in case". It quietly turns your card into a revolving loan.
- Approving a high mandate cap. A ₹10,000 cap on a ₹499 subscription removes the OTP checkpoint for any price hike below that.
- Ignoring pre-debit SMSes. They are your one chance to stop a wrong charge before it happens.
- Spreading subscriptions across five cards. One card for recurring bills keeps the audit simple and concentrates rewards.
- Forgetting mandates after closing a card. Move them to the new card first, or services will lapse.
The bottom line
Put your credit card bill on autopay for the total amount due, from an account that always has the balance. Route predictable bills through one rewards card that pays well on utilities, and check that card's mandate list every few months. If you are still choosing that card, the BestCard matcher can shortlist options based on what your monthly bills actually look like.
Frequently asked questions
What is an e-mandate on a credit card?
It is a standing instruction that lets a merchant charge your card on a recurring schedule, such as a monthly OTT subscription, insurance premium or utility bill. You authenticate once at setup, and later debits run automatically within the limits you approved.
Will I get an OTP for every autopay debit?
Not for smaller amounts. Under RBI's e-mandate framework, recurring debits below the prescribed limit go through without fresh authentication, but your bank must send a pre-debit notification before each charge. Debits above the limit need an OTP or other additional factor of authentication.
How do I cancel a credit card autopay?
Cancel it from the merchant's app or website, and also check your card issuer's mandate management page (net banking, card app or the SiHub-style portal some banks use). Cancelling at the bank level stops future debits even if the merchant keeps the subscription active.
Should I set my credit card bill on autopay for minimum due or total due?
Total amount due, if your bank balance can carry it. Autopay on minimum due avoids late fees but leaves the rest of the balance to attract interest, which is the most expensive form of borrowing most people ever use.
Related reading
- Can You Pay a Mutual Fund SIP with a Credit Card in India?
Can you pay a mutual fund SIP with a credit card? Why AMCs and apps say no, the costly workarounds to avoid, and a smarter way to use your card for investing.
- Credit Card Spends and Income Tax Notices: Limits to Know (2026)
Banks report high-value credit card payments to the tax department. See the ₹1 lakh cash and ₹10 lakh limits, what triggers a notice, and how to stay safe.
- Lifetime Free vs Paid Credit Card: Which Should You Choose?
Lifetime free or paid credit card? Use a simple break-even formula, real examples from cards like SBI Cashback and Amazon Pay ICICI, and avoid the common traps.