
Credit Card Interest Rates by Bank 2026: What Indian Banks Charge
18 September 2026 · BestCard Editorial Team
Most Indian banks charge between 3% and 3.75% a month on standard credit cards, which works out to 36% to 45% a year before compounding. HDFC and ICICI list 3.75% a month on most of their cards, while a handful of issuers, led by IDFC FIRST Bank, offer much lower starting rates. Below is what BestCard's card data shows bank by bank, and what those numbers cost you in rupees.
How credit card interest rates are quoted
Banks express the same rate in different ways, which makes comparison confusing:
- Monthly rate, such as 3.75% a month. This is how most Indian issuers state it in their terms.
- Annual rate (simple), the monthly rate × 12. 3.75% a month is 45% a year.
- Annualised compounded rate, which accounts for interest on interest. 3.75% a month compounds to about 55.5% a year. That's why you'll see Axis My Zone's revolving APR listed as 55.55% a year.
All three can describe the same card. When comparing, convert everything to the monthly figure. Our explainer on credit card APR goes deeper into the difference.
Interest rates by bank
These are the finance charges recorded in BestCard's latest card data. Not every card from each bank is listed, and rates can vary within a bank's range based on your profile.
| Bank | Card | Interest rate in BestCard data |
|---|---|---|
| HDFC Bank | Most HDFC cards | 3.75% a month |
| HDFC Bank | HDFC Infinia | 23.88% APR |
| HDFC Bank | HDFC Freedom | About 45% APR |
| HDFC Bank | Micro Enterprise Business | 1.5% a month (18% a year) |
| ICICI Bank | Most ICICI cards | 3.75% a month |
| ICICI Bank | Business Micro | 1.5% a month (18% a year) |
| Axis Bank | Axis My Zone | 55.55% a year (annualised) |
| SBI Card | SBI Student Plus Advantage | 2.25% a month |
| IDFC FIRST Bank | IDFC FIRST Millennia | From 0.71% a month |
| Yes Bank | Yes Bank ACE | About 47.9% APR |
| Standard Chartered | Priority Visa Infinite | Up to 45% APR |
| Kotak Mahindra Bank | Kotak Biz | 42% annualised |
| Bank of Baroda | BOBCARD Scapia | 3.75% a month |
| Bank of Baroda | BOBCARD Uni GoldX | Up to 3.99% a month |
| AU Small Finance Bank | Paytm AU | 3.75% a month |
| AU Small Finance Bank | CA Metal | 2.99% a month |
| IndusInd Bank | Sāarthi Business | 2.49% a month |
| Union Bank of India | VISA Signature | 3% a month |
| City Union Bank | CSK Master Platinum | 3.5% a month |
| Punjab National Bank | PNB RuPay Platinum | 35.89% APR |
| Punjab National Bank | PNB Kiwi RuPay | 2.95% a month |
| Federal Bank | Visa Imperio | From 5.88% a year |
| Federal Bank | Secured (against FD) | 0.83% a month (9.99% a year) |
Issuers revise finance charges, and BestCard's data reflects the latest terms we have. Always check your card's Most Important Terms and Conditions (MITC) on the issuer's site before relying on any figure.
What the patterns tell you
Large private banks cluster at the top. HDFC and ICICI's standard 3.75% a month is typical of mainstream cards. Premium cards don't always mean lower rates: Infinia's 23.88% APR is lower, but many premium cards carry the same rate as entry cards.
IDFC FIRST and Federal Bank are the outliers. IDFC FIRST's cards start at much lower rates that can fall further with good repayment behaviour. Federal Bank's Imperio starts at 5.88% a year.
Secured and micro-enterprise cards are cheaper. FD-backed cards and government-scheme business cards charge 18% a year or less, because the bank's risk is lower.
Worked example: what 3.75% a month costs
Say you carry a ₹50,000 balance for one full month on a card charging 3.75% a month.
- Interest: 3.75% × ₹50,000 = ₹1,875
- GST at 18% on the interest: ₹337.50
- Cost for one month: ₹2,212.50
Leave it for a year without paying it down and the balance compounds to roughly ₹77,775 on interest alone (₹50,000 × 1.5555), before GST and any late fees. On a card at 0.71% a month, the first month's interest on the same ₹50,000 would be ₹355, plus ₹63.90 GST.
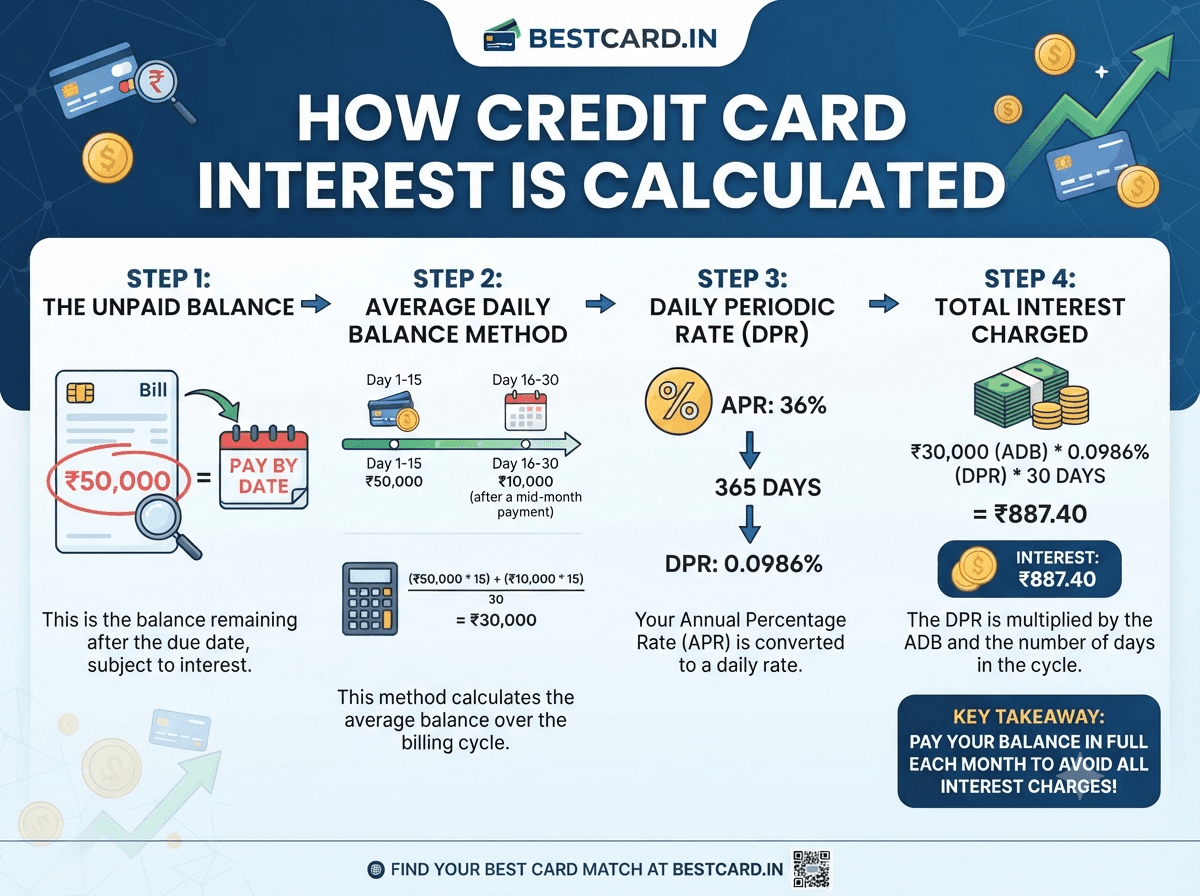
There's a second, hidden cost. When you carry a balance, most banks charge interest from the date of each transaction and new purchases lose their interest-free period until the full balance is cleared. So even your next grocery bill starts accruing interest right away. Our guide on how credit card interest is calculated walks through the daily balance method step by step.
The minimum due trap
Paying only the minimum due keeps your account in good standing but leaves the rest of the balance accruing interest at the full rate. On a 3.75% card, a balance can take years to clear this way. Read the minimum due trap for a month-by-month example.
How to find your card's exact rate
- Check the MITC. Every Indian issuer publishes a Most Important Terms and Conditions document listing finance charges.
- Look at your statement. Most statements show the applicable monthly rate.
- Ask the bank. Rates can be profile-based, so your rate may differ from the card's headline.
How to pay less interest
- Pay the total due every month. Interest is zero if you never revolve. Our interest-free period explainer shows how to time purchases.
- Move a balance you can't clear. A balance transfer or EMI conversion is usually cheaper than revolving. See the balance transfer guide.
- Use a low-rate card if you sometimes revolve. IDFC FIRST cards or an FD-backed secured card cost far less if a balance is unavoidable.
- Never withdraw cash on a card. Cash advances typically attract interest from day one plus a fee.
Bottom line
If you always pay in full, the interest rate on your card barely matters, and you should pick on rewards instead. If you sometimes carry a balance, the gap between 0.71% and 3.75% a month is worth far more than any cashback. SBI Card's Student Plus Advantage at 2.25% a month and Axis Bank's mainstream cards like My Zone show how much rates vary even within big issuers. For a card matched to how you actually use credit, try the BestCard matcher.
Frequently asked questions
What is the typical credit card interest rate in India?
Most standard cards from large banks charge around 3.5% to 3.75% a month on revolving balances, which is 42% to 45% a year before compounding. HDFC and ICICI list 3.75% a month on most of their cards in BestCard's data.
Which bank has the lowest credit card interest rate?
IDFC FIRST Bank stands out, with IDFC FIRST Millennia starting at 0.71% a month. Federal Bank's Imperio card lists a starting APR of 5.88% a year, and FD-backed secured cards like Federal Bank's charge 9.99% a year.
Is GST charged on credit card interest?
Yes. 18% GST applies to finance charges, late fees and other card fees in India, so the effective cost is higher than the headline rate.
How do I avoid paying credit card interest?
Pay the total amount due, not the minimum, by the due date every month. If you carry any balance, most banks charge interest from the transaction date and new purchases lose their interest-free period until the balance is cleared.
Related reading
- Dynamic Currency Conversion Explained: Always Pay Local
Dynamic currency conversion explained: why paying in rupees abroad costs more, a worked example, how to spot DCC at terminals and ATMs, and which cards help.
- Credit Card Utility and Education Transaction Fees Explained
How credit card fees on utility bills and education payments work in India, when they apply, how GST adds to them, and practical ways to avoid or reduce them.
- GST on Credit Card Fees and Charges Explained (2026)
Which credit card charges attract 18% GST in India, from annual fees and interest to forex markup and late fees, with rupee examples and ways to pay less.